
How to Choose a Bad Credit Mortgage Broker in the UK
If you're looking to choose a bad credit mortgage broker, you're in the right place. We hear from a lot of people who were told no by the wrong broker, so here is what we would check.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Quick answer: How do you choose a bad credit mortgage broker?
Check five things, in this order:
- They are on the FCA register.
- They place bad credit cases regularly.
- They can explain which lenders they reach.
- Their fees are published.
- Their reviews mention cases like yours.
Why ask A Little Mortgage Advice?
Because we're the broker people often ring second. Ten of our 185 Google reviewers came to us after another broker or lender had turned them down, and we were named Best Independent Bad Credit Mortgage Broker 2024, Essex, in the SME News UK Enterprise Awards. In 2026 BFSI Insider selected us as Adverse Credit Mortgage Brokerage of the Year, Essex.
... I was told by another broker I couldn’t lend a penny and Angela and Nicole helped me right the way through. ...
Reviews are individual experiences. Every case is different and approval is never guaranteed.
We'd rather you checked us the same way you check anyone else, so we've used ourselves as the example below.
What should you check first? The five checks at a glance
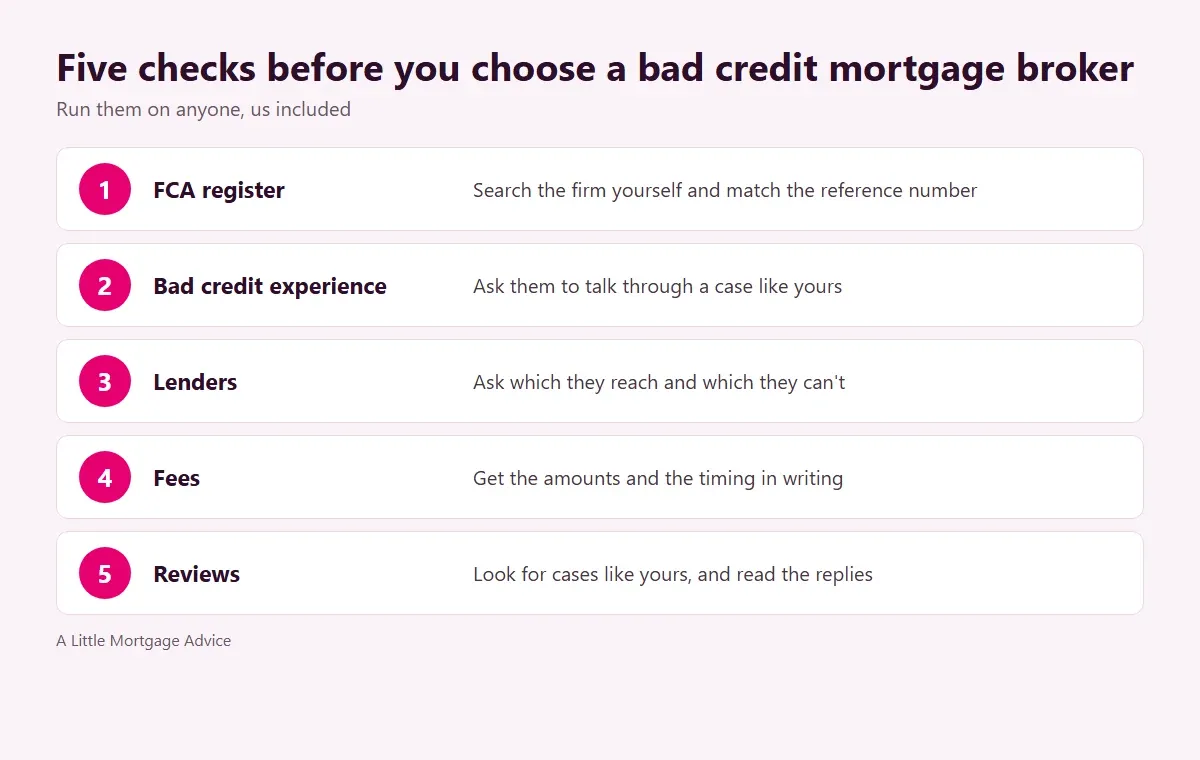
| Check | What good looks like | How to test it |
|---|---|---|
| FCA status | Listed on the Financial Services Register, with mortgage permissions | Search the register yourself |
| Bad credit experience | Places these cases regularly, and can talk through one | Ask for an anonymised example |
| Lenders | Tells you plainly which lenders it can reach | Ask what is outside its reach |
| Fees | Published, with the amounts and the timing | Ask for the Terms of Business |
| Reviews | Real, recent, and mention cases like yours | Read the low-star ones and the owner's replies |
Is the broker regulated by the FCA?
This is the check to do before any other, and it takes about two minutes. Anyone advising on a regulated mortgage must be authorised by the Financial Conduct Authority, or be an appointed representative of a firm that is.
To check a mortgage broker on the FCA register:
- Go to the Financial Services Register at register.fca.org.uk.
- Search the firm's name or its firm reference number.
- Check its status, and that it shows mortgage activities.
- If it's an appointed representative, check who its principal firm is.
What is an appointed representative?
It's a firm that can carry out certain regulated business on behalf of a principal firm. The principal firm is authorised, and it's responsible for that business. If something goes wrong, you can complain to the appointed representative or to its principal firm, and you may then be able to go to the Financial Ombudsman Service. The FCA says some activities by an appointed representative may not be protected, so check the principal firm's entry as well.
We're a good example. A Little Mortgage Advice is a trading style of A Little Advice Limited, an appointed representative of The Right Mortgage Limited, which is authorised and regulated by the Financial Conduct Authority. Our FCA firm reference is 1006474, so you can look us up.
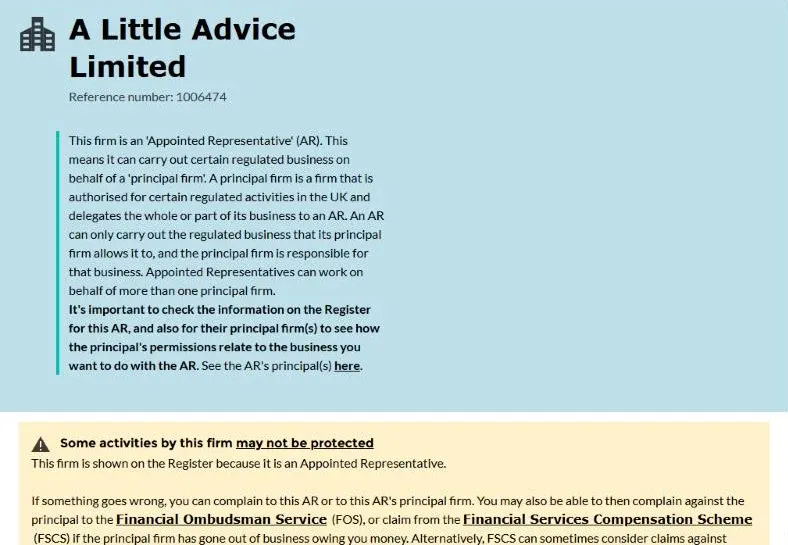
| On the register | What it tells you |
|---|---|
| Firm reference number | The number to search, and to match against the broker's website |
| Status | Whether the firm is authorised, or an appointed representative |
| Principal firm | The firm responsible for an appointed representative's work |
| Trading names | Other names the firm uses, so check the name you were given |
| Permissions | What the firm is allowed to do. Look for mortgage activities |
If the broker isn't on the register, don't go any further. The FCA's own advice is to check before you deal with anyone, and MoneyHelper explains what to do if you're unsure.
Do they place bad credit cases regularly?
A lot of brokers will take a bad credit enquiry. Fewer place these cases week in, week out, and the difference shows when a file gets awkward. Lending to people with an impaired credit history is a small part of the market: 0.85 per cent of UK mortgage lending in 2026 Q2, according to our UK bad credit mortgage statistics, though that still came to £2.57 billion across 2025, the highest annual total since 2008.
So ask them to talk through a case like yours. A broker who does this work can tell you how lenders read a CCJ against a default, how much the age of a marker matters, and what they'd do first. In Angela's words:
We thrive on helping people that have been turned down by other mortgage advisors because just like in your case, all the information was there, the jigsaw pieces were just in the wrong places ...
If you want to test them, our pages on CCJs, defaults and missed payments show the kind of detail to expect.
Want to ask us the same questions? The first conversation is free. Call 01268 387898
Which lenders can they reach, and which can't they?
Every broker has limits, and a good one will tell you what they are. Some are tied to one lender or a small panel. Others reach much more of the market. Ask these three questions:
- Which lenders do you use for cases like mine?
- Are there any deals you can't get, such as those only available by going direct to a lender?
- Do you use specialist lenders, or only the high street?
What you want is a plain answer. Specialist lenders matter on a bad credit case, because a human underwriter reads the file instead of an automated score. Here is what an underwriter checks.
Do they understand your income as well as your credit?
Credit is rarely the only thing that needs explaining. If you're self-employed, the question is how a lender reads your accounts as well as your file. According to analysis from Jones & Young, the typical home in England cost 18.6 times the typical self-employed person's income in 2024. For employed people, using the same HMRC data, it was 10 times. That gap is why the way your income is presented can matter as much as the marker on your file.
So ask how they'd present your income. If you're self-employed, a director or on a new contract, see our self-employed and new job pages for what lenders look for.
How do they charge, and when do you pay?
Some brokers are paid by the lender. Others charge a fee, and bad credit cases often cost more because they take more work. Neither is wrong, as long as you know the amount and the timing before you start. Ask for it in writing.
Here's ours, from our published Terms of Business, as a worked example:
| Standard case | Complex case, including adverse credit | |
|---|---|---|
| At decision in principle | £199 | £199 |
| At mortgage offer | £495 | Up to £1,295 |
| Total | £694 | Up to £1,494 |
The first conversation is free. The £199 isn't refunded if the case doesn't go ahead, which is why we'd tell you honestly first if we don't think it will.
Whichever broker you use, the fee is only part of the cost. Lender fees, valuation fees and solicitors' fees are separate, so ask for the full picture.
What do their reviews actually say?
Don't stop at the star rating. Read what people actually say, and look for your situation: bad credit, a CCJ, being turned down elsewhere. We hold 5.0 from 185 Google reviews, and ten of those reviewers say they were turned down or told to wait first. That's a more useful number than the 5.0.
Then read the owner's replies. A broker who writes a real answer to a real person is telling you how they work. Generic thank-yous tell you less. Check the dates too, because a review from five years ago says little about who's handling your case today.
What should you ask a broker before you sign up?
Take this list with you:
- Are you on the FCA register, and what's your firm reference number?
- How many cases like mine have you placed recently?
- Which lenders would you try first, and why?
- Will you search my credit file, and when?
- What do you charge, and when do I pay?
- Will the same person handle my case from start to finish?
- What happens if the first lender says no?
What are the warning signs of a bad broker?
Walk away, or at least slow down, if you hear any of these:
- "We guarantee you'll be accepted." Nobody can promise that.
- "We'll apply straight away and see what happens." Every failed attempt adds a hard search.
- No firm reference number, or one that doesn't match the register.
- Fees that only appear once you're committed.
- Being told to leave something off the application.
- Pressure to decide today.
If something has already gone wrong, you can complain to the firm and then to the Financial Ombudsman Service, which is free.
Common questions
Do I need a specialist broker, or will any broker do?
If your file is clean, any good broker will do. If it has CCJs, defaults or recent missed payments, someone who places those cases regularly will know which lenders to go to first.
Will speaking to a broker affect my credit score?
Not with us. The first conversation is free and nothing touches your file without us telling you first. Ask any broker the same question.
Should I use a broker or go direct to a lender?
If your credit is clean and you're happy with one lender's deal, going direct can work. On a bad credit case a broker can match your file to the right lender before anything is submitted. More in mortgage broker vs bank.
Can a broker help if my bank said no?
Often, yes. A decline from one lender is one lender's view of your file. Our guide to getting a mortgage after being declined sets out what to do next.
What qualifications should a mortgage broker have?
Advisers need a recognised qualification. Angela has held CeMAP since 2014, and she has more than ten years' experience advising on mortgages.
Does a bad credit broker need to be local?
No. A lot of this work happens by phone and email. We're based in Benfleet, Essex, and we advise clients across the UK.
How long does it take?
It depends on the case and the lender. Ask your broker for a realistic timeline before you start, and be wary of anyone who promises one that sounds too quick.
Can I change broker part way through?
Yes, though check your Terms of Business first in case any fee has already fallen due.
What should I bring to the first conversation?
Your credit reports from all three agencies if you have them, recent payslips or accounts, and a rough idea of your deposit. Our credit report page shows you how to read them.
Is the cheapest broker the best choice?
Not necessarily. A low fee means little if the application is declined, so weigh the fee against their experience with cases like yours.
Final thoughts from us
The points we'd leave you with:
- Check the FCA register first, because it takes two minutes.
- Ask a broker to talk through a case like yours.
- A good broker will tell you what they can't reach.
- Get the fees in writing, with the timing.
- Read what reviewers say, not just the stars.
- Nobody can guarantee you a mortgage, so be wary of anyone who says they can.
Sources
- Financial Services Register: FCA.
- Appointed representatives: FCA.
- Complaints: Financial Ombudsman Service.
- Lending to impaired credit borrowers: our UK bad credit mortgage statistics, from the FCA and Bank of England Mortgage Lenders and Administrators Return.
- House price to self-employment income: analysis by Jones & Young, using HMRC and ONS data.
- Fees: our Terms of Business.
- Reviews: our Google profile, verbatim, 31 October 2026. They are individual experiences: every case is different and approval is never guaranteed.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Thinking about speaking to a broker?
Ask us anything on this page.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.