
Can You Get a Mortgage With Missed Payments?
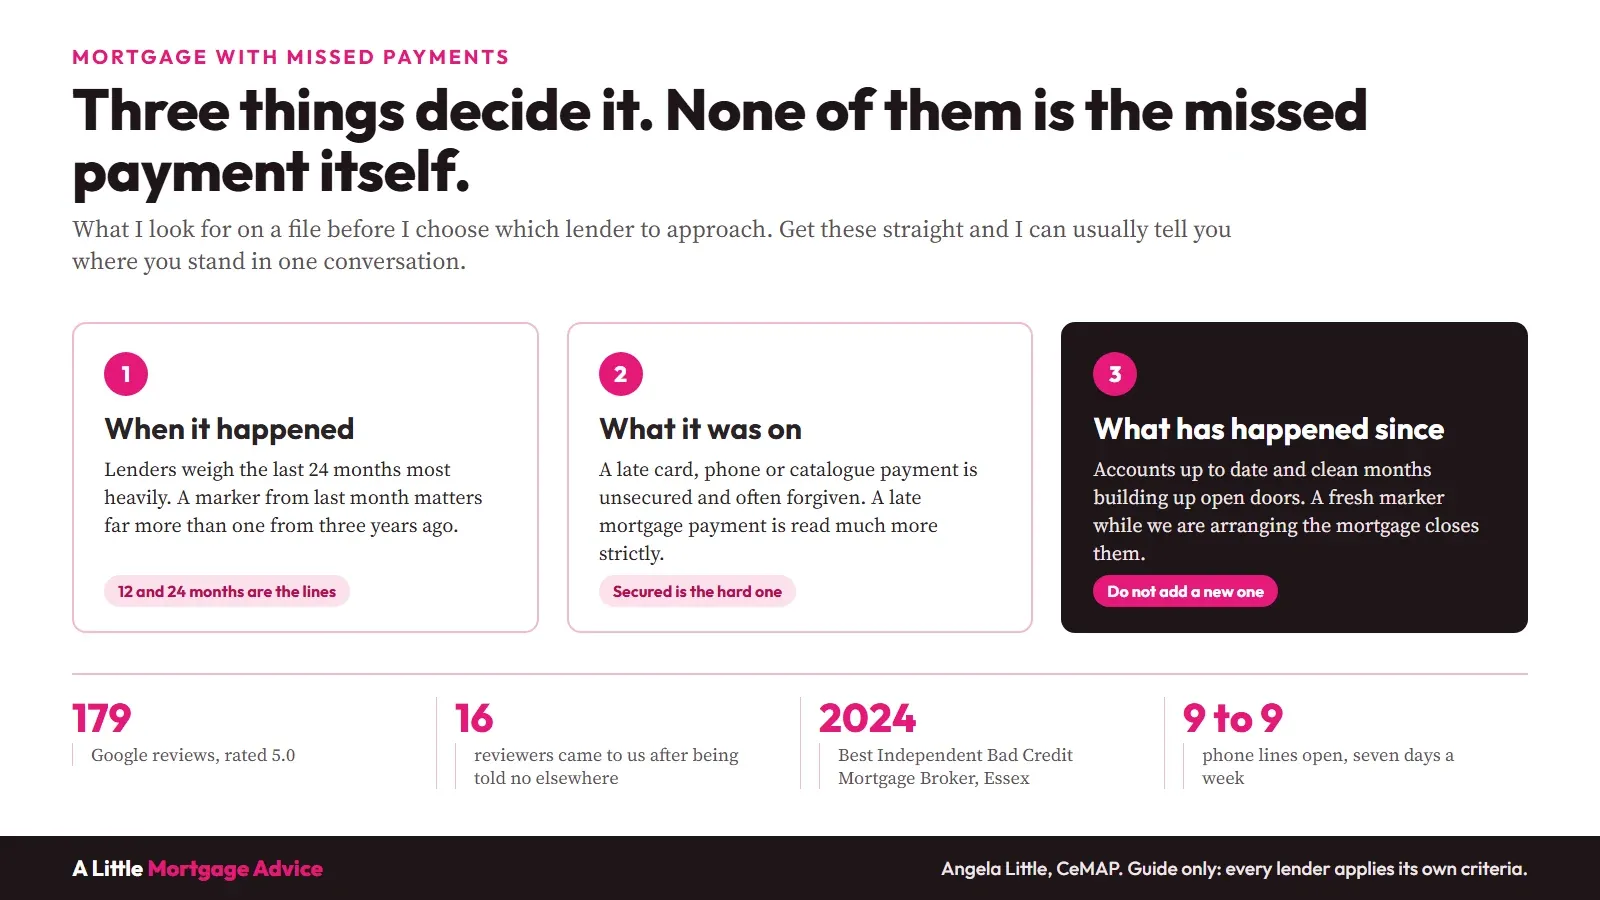
If you're looking to get a mortgage with missed payments, you're in the right place. Late payments are among the mildest things a credit file can carry, and on their own they rarely end the conversation.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Quick answer: Can you get a mortgage with missed payments?
Usually, yes. What matters is when the payments were missed and what they were on. One old late payment on a card or phone contract rarely changes anything. Recent markers, several of them, or a late payment on a mortgage shorten the list of lenders.

Where you might be
- One late payment on a card
- A run of missed payments
- A late mortgage payment
- Behind right now
- Declined by your own bank
Why speak to A Little Mortgage Advice about missed payments?
Bad credit is the work this firm is known for. We were named Best Independent Bad Credit Mortgage Broker 2024, Essex, in the SME News UK Enterprise Awards, and as a bad credit mortgage broker in Essex it is a lot of what I do.
Ten of our 185 Google reviewers came to us after another broker or lender had turned them down. Their words are on the reviews page in full.
Sooo happy! A Little Advice have done what other brokers couldn't and got us a mortgage offer! ...
Reviews are individual experiences. Every case is different and approval is never guaranteed.
I package the case myself and stay with it through the lender's questions, the solicitor and completion. You explain your late payments once, to me.
If the problem is the score rather than any single entry, start with a mortgage with a low credit score. If you already own and your deal is ending, see remortgaging with bad credit.
What counts as a late payment on your credit file?
Your credit file records a status for every account, every month. Pay on time and the month shows a 0. Pay a month late and it shows a 1. Two months late shows a 2, and so on. Those numbers are the markers lenders read, and they are the least serious entry a file can hold.
A payment that lands a few days late, inside the same month, usually never shows at all. It becomes a marker once the account is a full payment cycle behind, so you will see the agencies talk about 30 days.
 View it full size
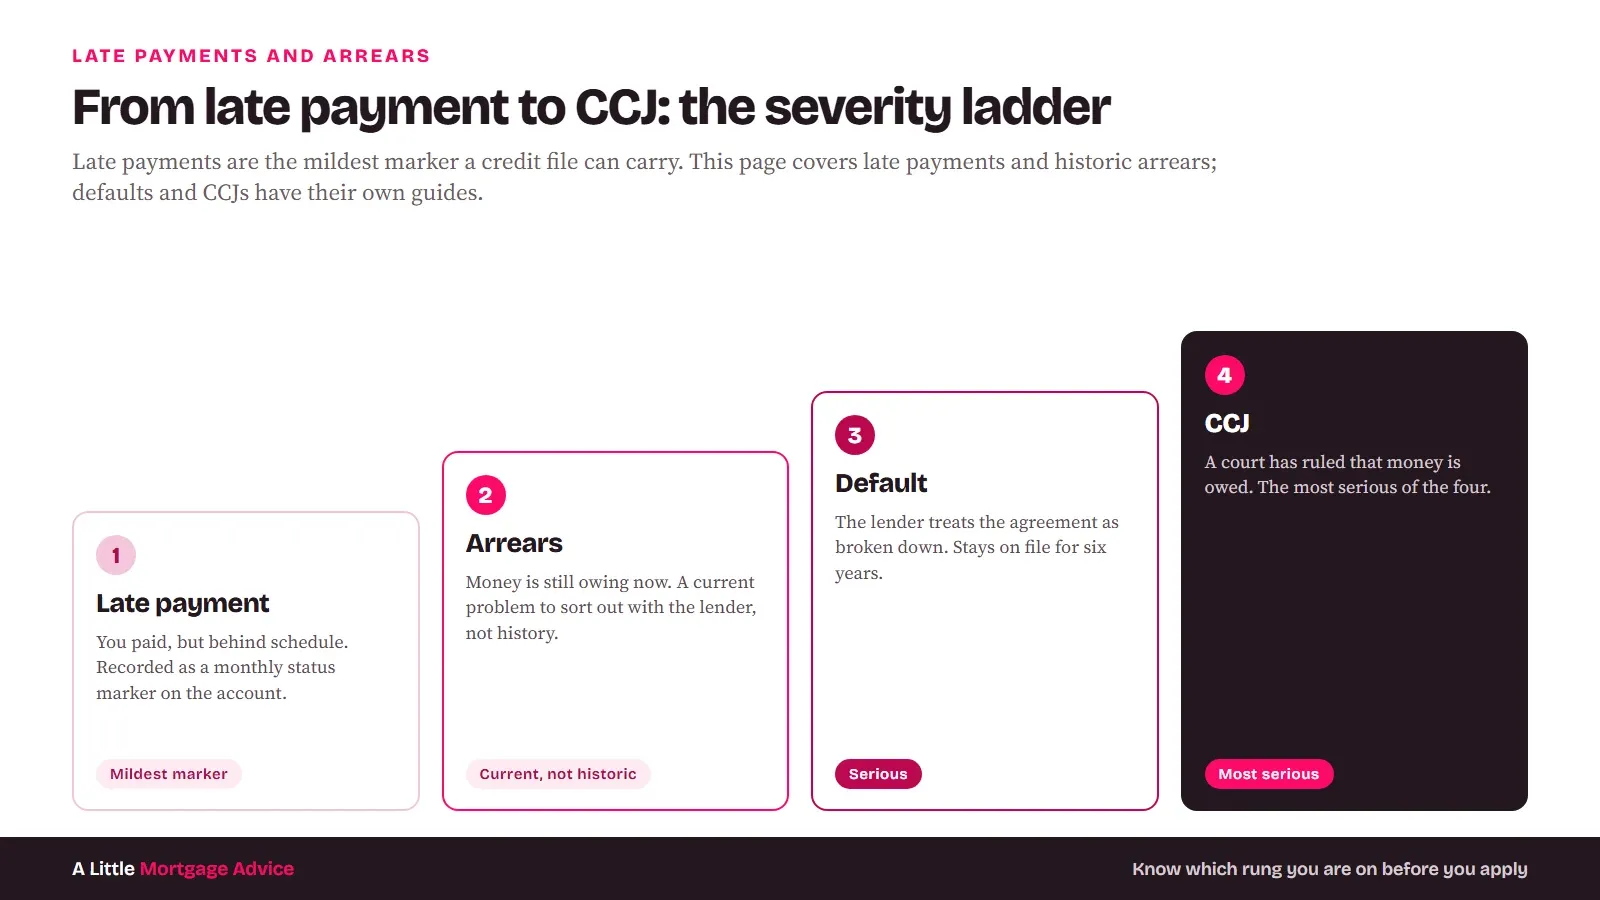
Late payments, arrears, defaults and CCJs: what is the difference?
They are steps on the same ladder, and the step you're on decides which lenders will look at you:
| On your file | What it means | How lenders usually read it |
|---|---|---|
| Late payment | You paid, but behind schedule | The mildest marker. A 1 or a 2 against the account |
| Missed payment | That month was not paid at all | Looks the same on the file as a late payment |
| Arrears | Money is still owing now | A current problem, not history. Covered at the end of this page |
| Default | The lender gave up on the agreement | Changes the list of lenders. See mortgages with defaults |
| CCJ | A court judgment, a step beyond a default | Changes the list again. See mortgages with a CCJ |
 View it full size
Does it matter whether the late payment was on a mortgage or a credit card?
More than anything else on this page. A late payment on a credit card, phone contract, catalogue or overdraft is unsecured, and plenty of lenders will overlook one or two once they are a year old.
A late payment on a mortgage or secured loan is read differently. You were late paying for your home, and a new lender notices. One old mortgage marker does not end the conversation, but it changes which lenders I go to first.
| Type of account | Examples | How it tends to be read |
|---|---|---|
| Unsecured | Credit card, phone, catalogue, overdraft | One or two, over a year old, are often overlooked |
| Secured | Mortgage, secured loan | Read more closely, and changes which lenders I start with |
Not sure how your file reads? Tell me when the payments happened and what they were on, and I can normally say which lenders will look at you. Call 01268 387898
Which mortgage lenders accept late or missed payments?
Lender criteria change every month, and every case is judged as a whole: income, deposit, the rest of your file, even the property. Treat what follows as the shape of the market rather than a promise from anyone. That market is growing: UK lenders advanced £2.57 billion to borrowers with an impaired credit history in 2025, the most since 2008, according to our UK bad credit mortgage statistics.
- High street banks. They run your file through an automated score, and no explanation changes what the score says. An isolated unsecured marker over a year old can still pass, especially where the account is up to date and the rest of the file is clean.
- Specialist lenders. They exist for the files the scorecards reject, and a human underwriter reads the file instead. Their products are usually tiered by how many months have passed since your last marker, and some ignore small utility, phone and mail order markers altogether.
When a file is at the mild end I try the high street first, because a yes there means a mainstream rate. What I would not do is pick a lender name off a comparison page and apply direct: a failed application leaves a hard search and a decline on your record, and the next one gets harder.
Take the above as an illustration built on experience rather than a promise. Criteria are fluid and date quickly, so speak to me before you rely on any of it. Finding the best deal open to you on the day is my job, and I will do that search on your behalf.
How long after a missed payment can you get a mortgage?
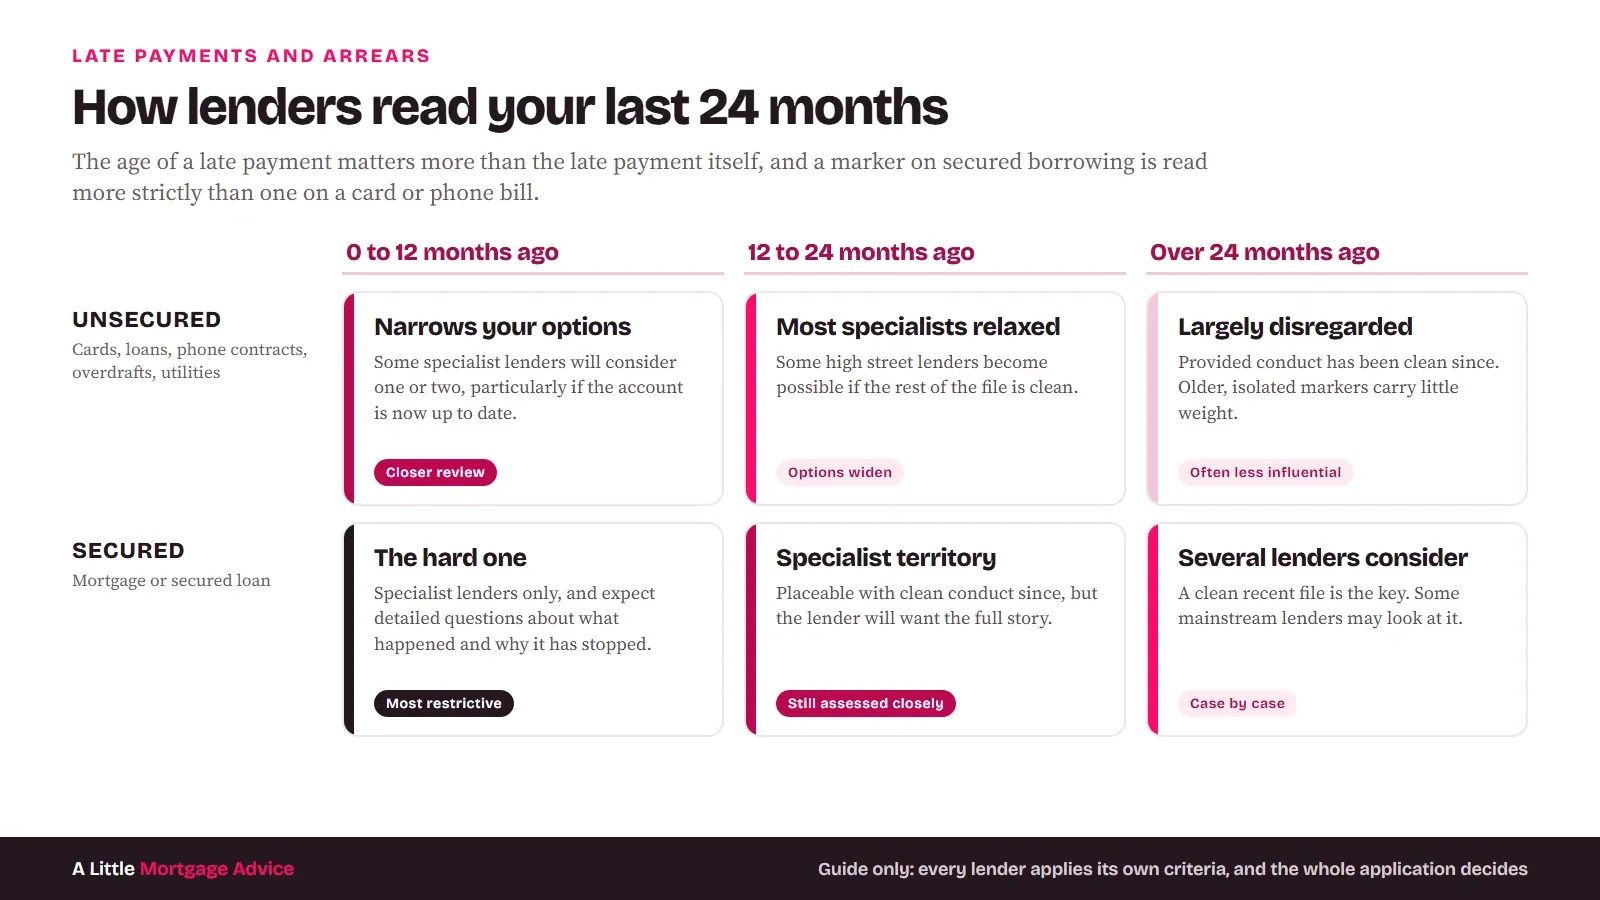
An underwriter does not read six years of history with equal attention. They look hardest at the last 24 months, and the question they are answering is whether your conduct is getting better or worse. A marker from 18 months ago matters more than one from three years back, and a marker from last month matters most of all.
| Age of the last marker | How it tends to read |
|---|---|
| Last few months | The hardest to place, because it reads as ongoing |
| Under 12 months | Usually a specialist lender, with a clear explanation |
| 12 to 24 months | More lenders open up, and the explanation still counts |
| Over 24 months, clean since | The list grows considerably |
| Six years | The marker drops off your file |
 View it full size
Nothing resets that window except clean months building up. The most useful thing you can do before applying is avoid adding a fresh marker while we arrange the mortgage. A phone bill slipping in the month before completion causes more problems than you would expect.
Markers stay on your file for six years from the date they are recorded, though their weight fades long before they drop off. The practical boundaries are at 12 and 24 months: if a marker is a few weeks away from one of those and you are not in a rush, waiting can be the better move. Most of the time the answer is to apply now with the right lender.
Will one missed payment affect a mortgage application?
Almost never on its own. A single unsecured late payment over a year old is close to invisible to most lenders. It starts to steer the case when the markers are recent, repeated, or on a mortgage.
Underwriters read the explanation as closely as the marker. A one-off event that has clearly ended is the easiest to place: a job loss, illness, a relationship breakdown, a direct debit that failed when you switched banks. What they struggle with is no explanation at all, or a pattern that is still going. Write one plain sentence for each marker, saying what happened and what has changed, and I put that in front of the underwriter.
What if you have a payment arrangement in place?
An arrangement is better than letting an account slide, but a lender will still see it. It shows you dealt with the problem, and it also shows the account isn't being paid in full. A lender will usually want to know what the arrangement was for, whether it's still running, and how you've kept to it since.
A finished arrangement that you stuck to is an easier story to tell than one that's still open. If yours is still running, tell me before we apply, so the lender hears it from us first and the explanation goes in with the case.
What if a missed payment on your file is wrong?
Mistakes happen, and they're worth fixing before you apply. Get your report from all three credit reference agencies, because an entry can appear on one and not the others. The ICO says to dispute it with the agency that holds it, and to complain to the ICO if the agency does not put it right.
Fixing a real mistake is different from removing a true entry. An accurate late payment stays for six years, whoever tells you otherwise.
Will late payments mean a higher rate or a bigger deposit?
Sometimes. If the high street takes you there is usually no premium at all. If the case needs a specialist lender, the rate is normally higher than the best mainstream deals, and some specialist products ask for a larger deposit. I do not print figures here, because they change monthly and your case will have its own answer.
Here is what a bigger deposit means in round numbers. This is an illustration, not a quote. On a £250,000 home, a 10 per cent deposit is £25,000 and a 15 per cent deposit is £37,500, so moving up a tier means finding another £12,500.
A slightly dearer mortgage you actually get, with a plan to remortgage once the markers age, beats a sharp rate you are declined for. Plenty of late payment cases start with a specialist lender and move to the high street at the first remortgage, and I put the review date in the diary on the day we complete.
A bigger deposit widens which lenders and products are in reach. A longer term helps the affordability sums but does nothing for the credit history, and the credit history is what got you declined.
Declined because of late payments? Do this next
A decline from one lender is one lender's view of your file. Do not apply anywhere else yet, because every failed attempt adds a hard search.
Get your report from all three credit reference agencies, write down what each marker was and why, and then call me. I will tell you which kind of lender should have seen the file in the first place. There is more in my guide to getting a mortgage after being declined.
- Get your credit report from all three agencies. People are often wrong about what their file says, and understanding your credit report shows you how to read it. Checking your own report is a soft search and leaves no mark.
- Bring every account up to date before you apply, not after.
- Talk to me before anyone runs a full application.
If you're looking for a new broker, here's how to choose a broker with bad credit.
What happens if you miss a mortgage payment right now?
Everything above is about old markers. If you are in arrears today, that comes first, and you're not alone: 80,490 UK homeowner mortgages were in arrears of 2.5 per cent or more in 2025 Q4, 0.92 per cent of the total and down 13 per cent year on year, according to our UK bad credit mortgage statistics.
Speak to your lender early: they are required to treat you fairly and to consider a payment arrangement. MoneyHelper explains the support your lender should offer, and StepChange gives free debt advice. You do not need to pay anyone for either.
Then talk to me. Part of the job is planning the route back: what to settle first, when the file becomes placeable, and which kind of lender that will be.
Missed payments and mortgages: your questions
Do late payments on a phone bill count?
They show on your file like any other account, but they are the most forgiven marker there is. Some specialist lenders ignore small utility and phone markers entirely.
Can I get a mortgage with late mortgage payments?
Yes, but it is the harder version. A recent one usually means a specialist lender and a full explanation. Once it is over two years old and everything since is clean, the list of lenders grows considerably.
How many late payments is too many?
There is no fixed number. Two or three unsecured markers spread across a bad year, all now up to date, is a common file and very placeable. Markers still appearing in the last few months are the problem, because that reads as ongoing.
Should I wait until they drop off my file?
Six years is a long time to put your life on hold. Usually we apply now and remortgage onto a cheaper deal later. Waiting only wins when a marker is weeks away from the 12 or 24 month line.
What happens if I miss my mortgage payment by two days?
If it lands inside the same month it usually never shows on your file. Your lender may still contact you or charge a fee, so it's worth calling them.
How long do late payments stay on your credit file?
Six years from the date they are recorded, though their weight fades long before that.
Can you have a good credit score with missed payments?
You can, particularly if they're old and everything since has been paid on time. A lender will still see the markers, because it reads the report and not only the score. Our low credit score page explains why.
Can you remortgage with missed payments?
Yes, often. Our remortgage with bad credit page covers how lenders treat it when you already own.
What is the difference between a missed payment and a default?
A missed payment is a month that wasn't paid. A default means the lender has ended the agreement, which is more serious. Our defaults page covers it in full.
Will talking to you affect my credit score?
No. The first conversation is free and nothing touches your file without me telling you first. A full application is a hard search, which is why we choose the lender before anyone runs one.
Final thoughts from me
Before you do anything else, here is what I'd want you to know:
- Late and missed payments are the mildest thing a credit file can carry.
- When they happened and what they were on matter more than how many there are.
- Underwriters look hardest at the last 24 months.
- A late payment on a mortgage is read differently from one on a card or phone.
- Don't apply anywhere after a decline until you know what your file says.
- If you're behind today, speak to your lender first. Everything else can wait.
Sources and further guidance
- Experian: how a default affects your credit profile, for how long markers stay and how to dispute one
- FCA Handbook, MCOB 13: what lenders must do when a borrower is in arrears
- Arrears and lending figures: our UK bad credit mortgage statistics, from UK Finance and the FCA.
Checked on 17 September 2026. Lender criteria change constantly, so confirm the current position before relying on anything here.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Missed a few payments?
Lenders look at when it happened and why. Talk it through with us before you apply anywhere.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.