
Can You Get a Mortgage With a CCJ?
If you're looking to get a mortgage with a CCJ, including one you have already paid off, you're in the right place. I once placed a first-time buyer with an unsatisfied CCJ with a high street building society, so I start with the detail of your judgment rather than the label on it.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Quick answer: How soon after a satisfied CCJ can I get a mortgage?
There is no fixed waiting period. Some specialist lenders will consider a satisfied CCJ inside a year, more open up as it ages, and after six years it drops off your credit file. The amount, when you paid it and your deposit count as much as the date.

Where you might be
- One CCJ, now satisfied
- An unsatisfied CCJ
- A CCJ you think is wrong
- Buying with a partner
- Declined somewhere else
Why speak to A Little Mortgage Advice about a CCJ?
A CCJ narrows the list of lenders. Knowing who is still on it is the job of a mortgage broker. I start with the date, the amount, whether it is paid and why it happened. Then the rest of the file, the deposit and the property. Only then do I go to a lender, with the explanation and the evidence together.
I used Angela for a mortgage i thought I'd never, EVER get, because of adverse credit- however, Angela's persistence and hard working got me my mortgage offer after many obstacles ...
Reviews are individual experiences. Every case is different and approval is never guaranteed.
What is a CCJ?
A County Court Judgment, or CCJ, is a court decision in England and Wales confirming that you owe money and how it must be paid. Scotland has its own system, where the equivalent is a decree.
A CCJ stays on the Register of Judgments, Orders and Fines, and on your credit file, for six years from the date it was registered. Only 11.8 per cent of the 5.39 million records on the Register are marked as satisfied, one of the figures in our UK CCJ statistics.
How long after a CCJ is satisfied can you get a mortgage?
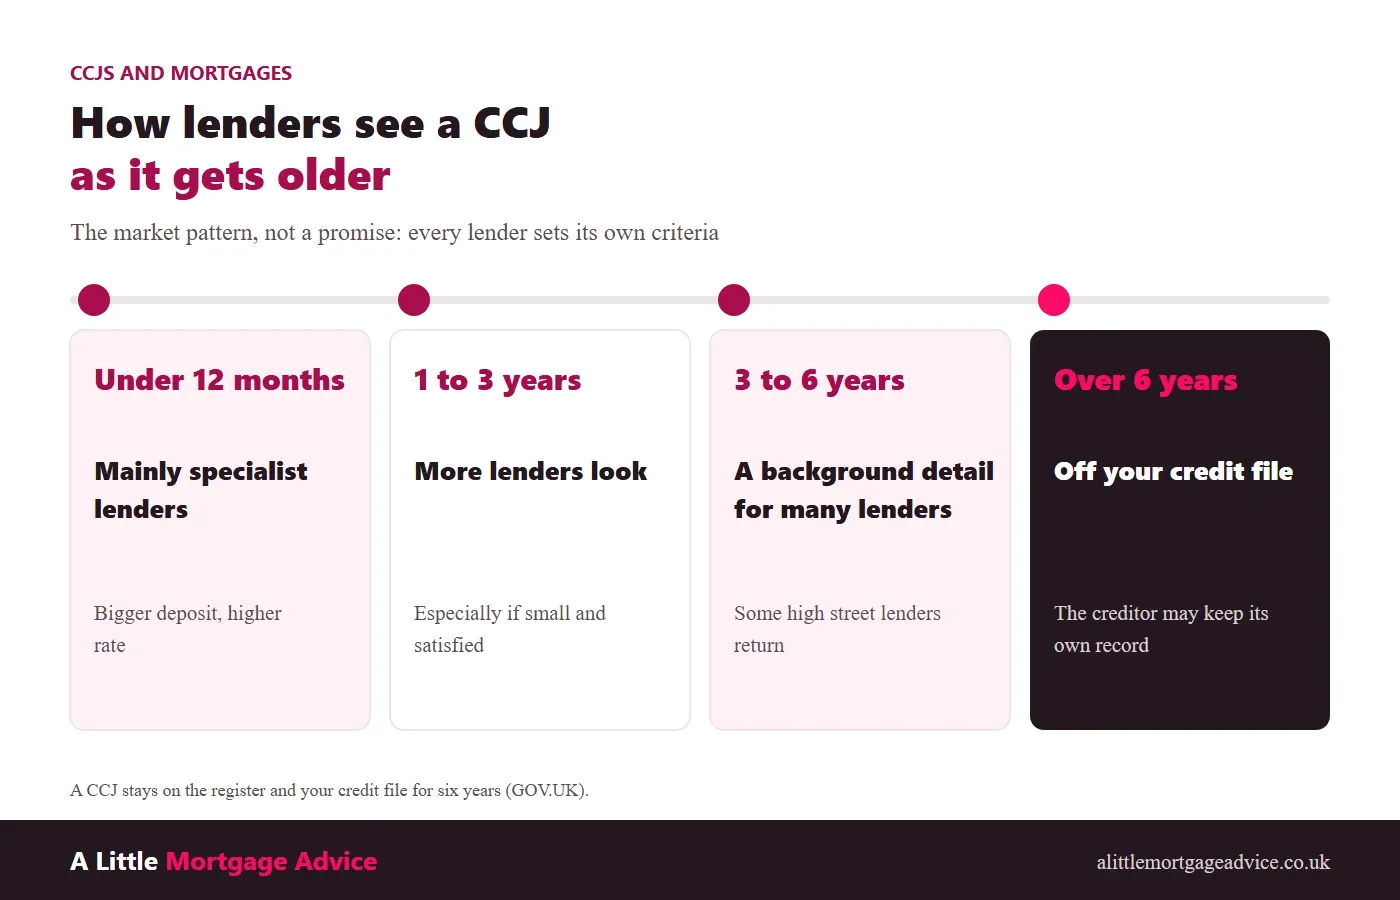
The registration date matters more than any waiting rule. The market pattern runs like this, though no lender promises it and each sets its own criteria.
| Age of the CCJ | How lenders see it |
|---|---|
| Under 12 months | Mainly specialist lenders, bigger deposit, higher rate |
| 1 to 3 years | More lenders look, especially if it is small and satisfied |
| 3 to 6 years | A background detail for many; some high street lenders return |
| Over 6 years | Off your file, though the creditor may keep its own record |
 View it full size
If a CCJ is one of several marks on your file, our adverse credit mortgage broker page covers how lenders read them together.
Does the size of the CCJ matter?
Yes. A small, satisfied CCJ reads very differently from a large one. Some lenders barely count a satisfied judgment below their own limit, and the limits vary, so I check them case by case.
The FCA treats a borrower as credit impaired where CCJs totalling more than £500 were registered in the last three years. It is a reporting definition, not a lending rule.
Most CCJs sit well below that. The median new consumer CCJ in England and Wales was £607 in early 2026, and 45 per cent were under £500 (Registry Trust).
Is a satisfied CCJ better than an unsatisfied one?
Usually, yes. Lenders view a satisfied CCJ more favourably because the debt was cleared, and some that turn down unsatisfied judgments will consider satisfied ones. It still does not guarantee an approval or a rate.
When you pay changes what the record shows:
- Paid in full within one month of the judgment: it can be removed from the register.
- Paid after one month: it is marked as satisfied, and stays on the register for six years showing it was paid.
- Not paid: it stays for six years, shown as unsatisfied.
How do you prove a CCJ is satisfied?
Get the court's certificate. Send form N443, or a letter, to the court dealing with your case, with a £19 fee payable to HMCTS.
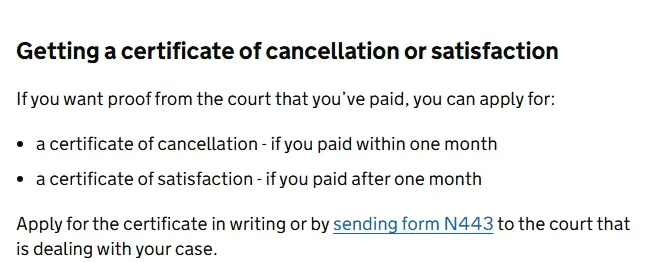
Then check the record has changed: a register search costs £6 to £10. Check Experian, Equifax and TransUnion too, as lenders use different ones. Keep the certificate and proof of payment. A lender will often ask for both.
Can you get a mortgage with an unsatisfied CCJ?
It can be possible. One first-time buyer came to me with an unsatisfied CCJ, expecting it to stop the purchase. I placed the mortgage with a high street building society.
Got me a mortgage with ease even though I have a unsatisfied CCJ.
That is one real outcome, not a pattern. It worked because that file met a lender prepared to consider it.
Can you get a joint mortgage if one of you has a CCJ?
Often, yes, but both of you are assessed. One clean credit history does not cancel out the other person's CCJ, though it can help through income and deposit.
Leaving someone off changes who owns the home. If you plan to add them later, adding someone to a mortgage explains what the lender checks.
Will you need a bigger deposit or pay a higher rate?
You may face a larger deposit or a higher interest rate than someone with a clean history. I can't give a universal percentage: how a CCJ affects the offer depends on the age, value and status of the CCJ and the rest of the application.
How lenders use your score is in a mortgage with a low credit score.
Should you apply now or wait?
Waiting helps in some cases. Find the one that fits:
- The CCJ is wrong or not yours: deal with that first, as below.
- It is recent or unpaid: have it looked at before applying, and see how to improve your chances with bad credit.
- It is five and a half years old: waiting a few months for it to drop off can be the honest advice.
- You have already been declined: find out why before trying another lender.
A run of declines makes the next lender more cautious. Remortgaging? See remortgaging with bad credit.
What if the CCJ on your file is wrong?
If the details are wrong, contact the court that made the judgment, then check the credit reference agencies have updated. If you do not owe the money, or never received the claim, you can ask the court to set the judgment aside on form N244.
I had 2 CCJs put on me wrongly even during the process of application ... a lender thoroughly dug into my accounts as they thought I was laundering money.
Fixing the record is a separate job from asking a lender to accept a genuine CCJ. The record comes first.
Common questions
Does a CCJ automatically stop you getting a mortgage?
No. It narrows your options, but the decision rests on the CCJ itself and the rest of the application: when it was registered, how much it was for, whether there are multiple CCJs, whether it has been paid, how you have managed credit since, and whether the deposit and affordability work.
Will a satisfied CCJ still show on my credit file?
Yes, for six years from the date it was registered, unless you paid in full within a month and had it removed. Marking it satisfied does not take it off your file or restart the clock. It changes how a lender reads it, because the record now shows the debt was paid.
Can I get a mortgage with a CCJ from the last 12 months?
Sometimes, mostly through a specialist lender, with a larger deposit and a clear explanation of what happened. A recent CCJ that is small and already satisfied is a far easier case than a large unpaid one. Have the file reviewed before any application, so a decline does not add to the problem.
Should I pay off a CCJ before applying for a mortgage?
Often it helps, because some lenders only consider satisfied judgments. Weigh it against your deposit first. Clearing a small, old CCJ with deposit money is not always the better route, and the right order depends on which lenders are open to your case.
Will talking to you affect my credit file?
No. A conversation is not an application, so talking to me leaves no search on your file. A lender only searches your credit file once you have agreed to an application, and by then you will know which lender it is and why it was chosen.
Sources and further guidance
- GOV.UK: CCJs and your credit rating
- GOV.UK: cancel a county court judgment
- Registry Trust, keeper of the register
- UK CCJ statistics
Checked 4 October 2026. Fees and criteria change.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Also worth a look
-
 Bad credit mortgages Bad credit does not always mean no mortgage. Bad credit mortgages are something of a speciality for us: matchi…
-
 Mortgage with defaults Yes, it can be possible. A default does not get the same answer from every lender. What matters is the type of…
-
 Mortgage with missed payments If you're looking to get a mortgage with missed payments, you're in the right place. Late payments are among t…
Got a CCJ? Talk to us.
When it was registered, how much it was for and whether it is satisfied all make a difference to lenders. This is what we deal with every day.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.