
Can You Get a Mortgage on Probation at a New Job?
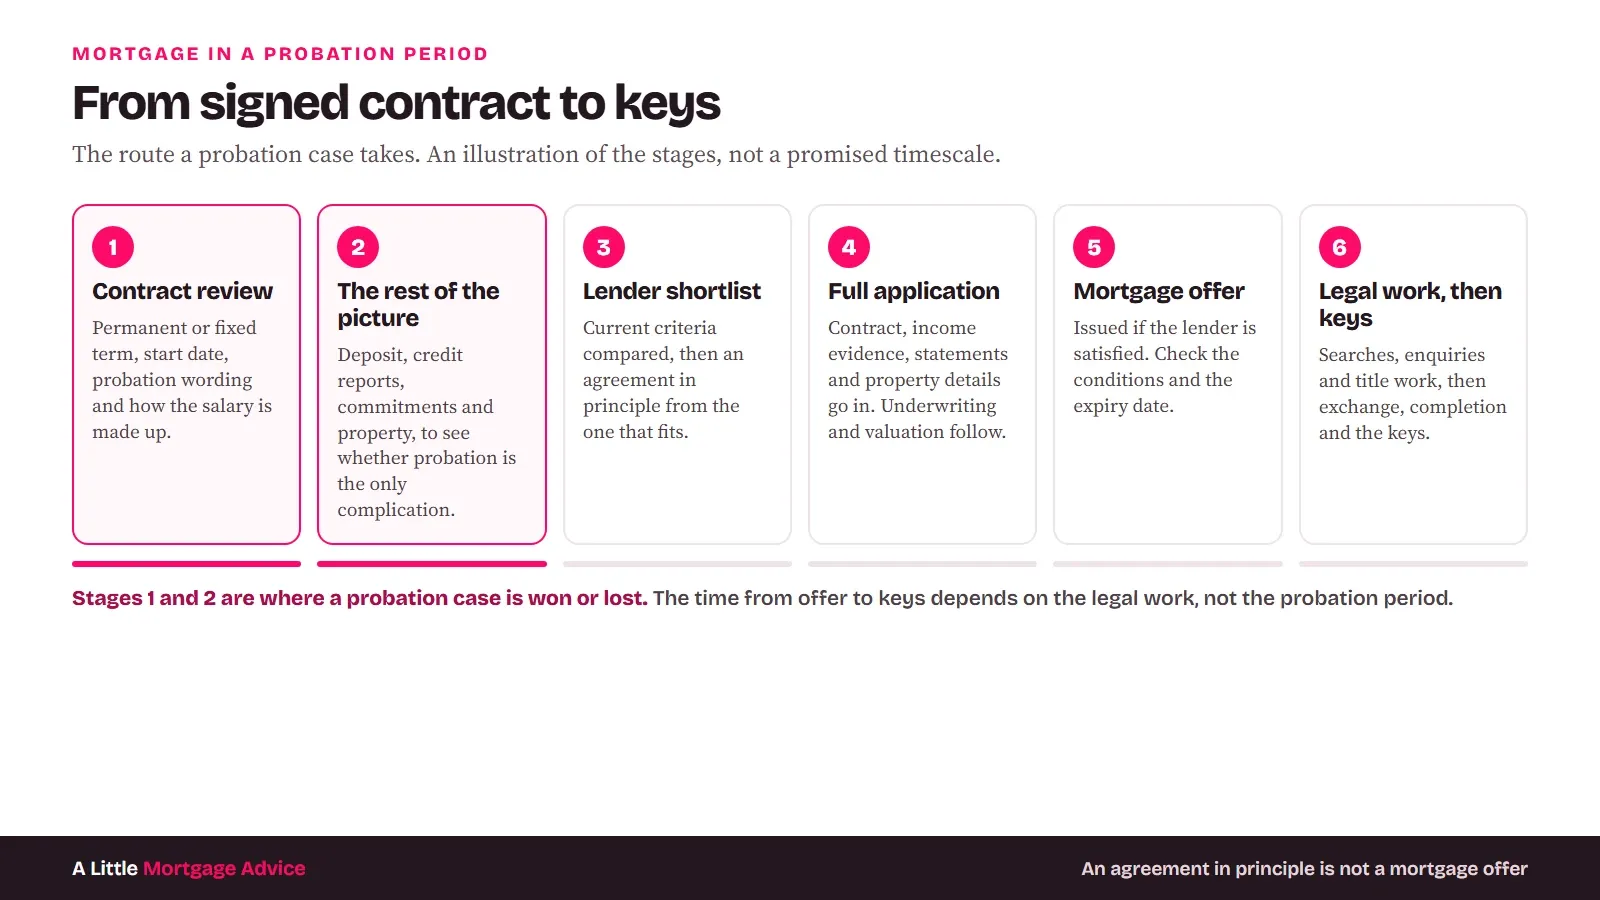
If you're looking to get a mortgage while you're on probation at work, you're in the right place. I start with your employment contract, because whether the probation sits inside a permanent job decides more than the probation itself.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Quick answer: Can you get a mortgage while on probation?
Often, yes. A permanent contract with a three or six month probation period is acceptable to several mainstream lenders, some from your first month. A purely probationary contract, where the employer decides later whether to keep you, is harder. Your payslips, deposit, credit file and affordability still count.

Where you might be
- In a 3 to 6 month probation period
- Job offer signed, not started yet
- First payslip not arrived
- Career change into a new industry
- Turned down by the high street
Why speak to A Little Mortgage Advice about a probation mortgage?
Because probation is where lender rules differ most, and a declined mortgage application leaves a hard search behind. I read the contract before I mention a lender, then put it beside your deposit, credit reports and the property, so the application only goes where the published rules fit.
... Where i differ from a lot of Mortgage Brokers is that i deal with the whole process including all the pre underwriting and dealing with the lenders and solicitors personally ...
Every case is different and approval is never guaranteed.
 View it full size
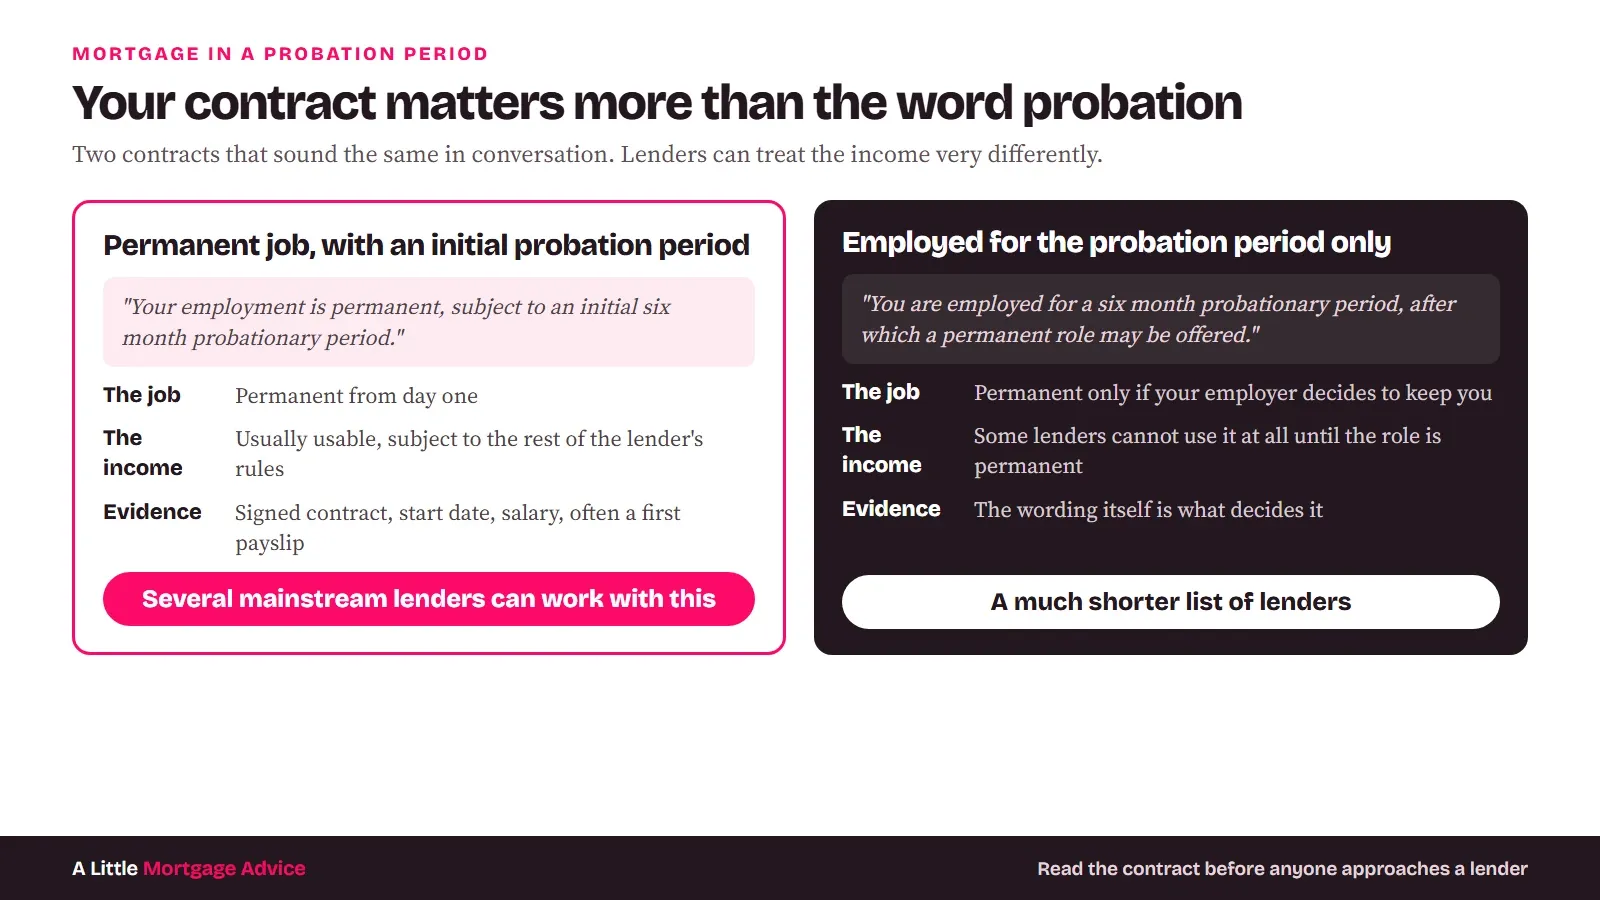
Why does your contract matter more than the word probation?
A contract can say your job is permanent from day one, with an initial probationary period. It can also say you are employed only for the probationary period and may be offered a permanent role afterwards. The two sound alike. Lenders treat the income very differently.
 View it full size
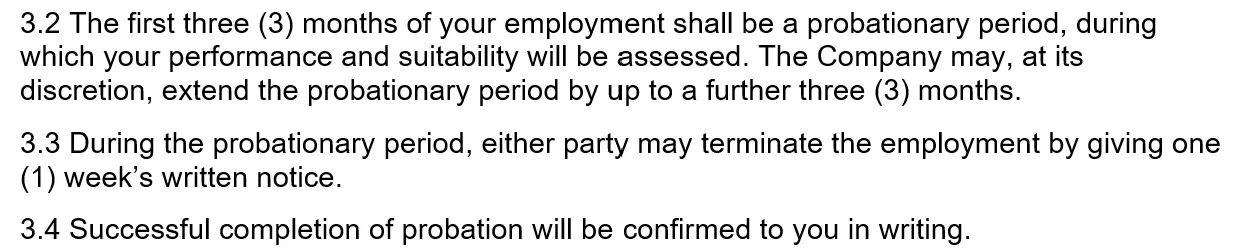
Halifax's criteria show it: probationary income counts where the probation is part of a permanent contract. Where the contract is purely probationary, that income cannot be used.
First I check the contract type, start date, probation length, basic salary, any guaranteed bonus, and whether your first payslip has arrived.
Which lenders accept a mortgage on probation?
There is no single probation lender. These five publish their rules, and the differences matter:
| Lender | Published position on probation | What can still stop the case |
|---|---|---|
| Accord Mortgages | Permanent role; no minimum time in the job | The role must be permanent and sustainable |
| Nationwide | Considers probation, even in the first month | First month: basic income only |
| Virgin Money | Accepts probation on a permanent contract | No first payslip yet |
| Halifax | Uses the income if the job is permanent | A purely probationary contract |
| NatWest | Can consider probation | Needs six months' continuous employment |
Read on 17 September 2026 from each lender's intermediary pages. They are examples, not a full panel, and they change, so check with me before relying on them.
Does a probationary period affect how much you can borrow?
It can, mainly through which parts of your pay count. In the first weeks some lenders use basic salary only. Bonus, overtime and commission need a track record, so they may be left out until you have the payslips to show them.
The upside: if the new job pays more, a lender that accepts your contract can use the new salary straight away, so you may borrow more than you could before the move. If the figure you need depends on variable pay, waiting for a few months of payslips can change the answer. My mortgage calculator gives a first idea before we speak.
What will a lender want to see?
Getting the evidence together before a full application goes in saves questions later:
- Your signed employment contract or appointment letter
- Your first payslip if it has arrived, and recent payslips from the previous job where relevant
- Bank statements showing the salary landing and your normal spending
- A letter from your employer confirming the probation terms, where the lender asks for one
- Proof of deposit and where it came from, plus ID and address evidence
- A clear employment history, including any gaps
Not starting until next month? Some lenders will consider a signed contract for a job that begins shortly. Mortgages with a new job covers applying before you start, and fixed-term contracts.
Should you apply now or wait until probation ends?
There is no automatic answer, and "wait six months" is not advice unless someone has checked what waiting would change.
Applying now tends to make sense when the contract is permanent, a lender's policy fits your start date and evidence, the basic salary supports the loan, and waiting would cost you the property.
Waiting can help when the contract is purely probationary, when the lender you need wants a first payslip, or when the probation end date is close enough that a better range opens up.
What happens if you fail probation after the mortgage completes?
The mortgage carries on. Once it has completed, the lender does not re-check your job, and losing it does not end the mortgage. What matters then is how you keep up repayments, from your next job, savings or other income.
If money gets tight, speak to the lender early. They have to treat you fairly and consider options such as a payment arrangement, and MoneyHelper's guidance sets out what to expect. Before completion it is different: a change of job or failed probation has to be disclosed, and the lender may reassess the offer.
Can you remortgage while on probation?
Yes, and it can be easier than buying. A product transfer to a new deal with your current lender, with no extra borrowing, does not normally involve a new income check. Moving to a new lender, or borrowing more, means a full application, and then the probation rules above apply. Remortgaging covers the choice.
Common questions
Do I have to tell a lender I'm on probation?
Yes. The lender sees your contract, start date and payslips, and the application asks about your employment. Leaving probation out, or describing a purely probationary contract as permanent, is misleading the lender and can put the mortgage at risk. Telling me at the start lets me pick a lender whose rules already fit.
Do I need three months of payslips?
Not for every lender. Some will consider a signed open-ended contract or an appointment letter, while others want a first payslip, or a longer history where the income is variable. There is no single rule across the market, which is why the lender is chosen around your documents.
Can I get a mortgage on probation as a first time buyer?
Yes. Being a first time buyer doesn't change the probation rules, though it often means a smaller deposit, which narrows the lender list a little further. Choosing a lender that accepts both your contract and your deposit at the first attempt matters more. First-time buyer mortgages covers the rest of the process.
Sources and further guidance
- Lender positions read on 17 September 2026 from each lender's intermediary criteria: Accord Mortgages, Nationwide for Intermediaries, Virgin Money for Intermediaries, Halifax Intermediaries, NatWest Intermediary Solutions
- MoneyHelper: falling behind with mortgage payments
Checked 5 October 2026. Lender criteria change without notice.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Also worth a look
-
 Specialist mortgages Plenty of good borrowers simply do not fit the template a high-street scorecard expects: income that arrives i…
Still in your probation period?
You do not always have to wait six months. With an employer letter and the right lender it can often be done now.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.