
Can You Get a Mortgage With Defaults? How Recent Is Too Recent?
Yes, it can be possible. A default does not get the same answer from every lender. What matters is the type of account, when it defaulted, how much it was for, whether it has been paid and how you have managed since.
A small phone bill from several years ago and a recent default on a loan are very different cases, so I look at the entry itself before anyone mentions a rule like waiting two years.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk

Can you get a mortgage with a default?
It can be possible. Lenders weigh how old the default is, how much it was for, what kind of account it was on and whether it has been paid, alongside your deposit, affordability and how you have managed credit since. A recent default on a mortgage or loan narrows the choice far more than an old, small phone bill.
Where you might be
- A default from a hard patch
- More than one default
- A default not yet paid
- A phone or utility default
- Declined because of a default
What is a default on your credit file?
A default is recorded when you have fallen well behind on a credit agreement and the lender treats the agreement as broken down. It usually follows three to six months of missed payments, although each lender's terms differ. It is more serious than a late payment, and different from a County Court Judgment: a CCJ comes from a court, while a default is recorded by the lender.
A default stays on your credit file for six years from the date of default, whether or not you pay it. Paying it marks the account as satisfied, but the entry stays until the six years are up unless it was recorded in error.
How do lenders weigh the age, size and type of a default?
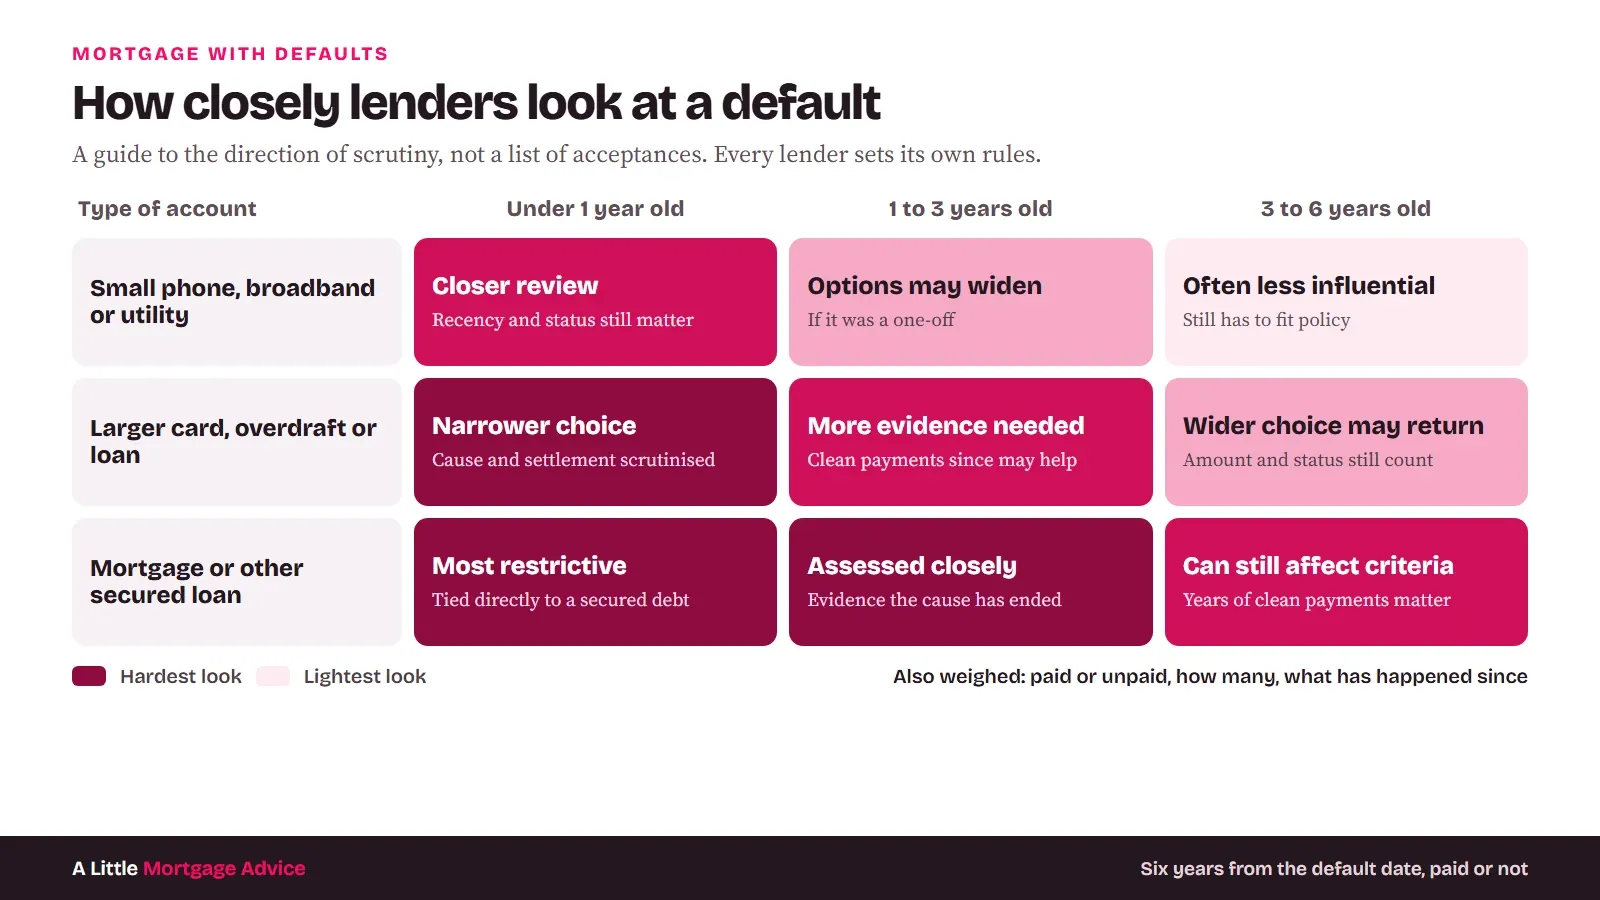
No single matrix is shared by every lender, and each one sets and changes its own rules. The pattern below shows how age, size and account type tend to change the level of scrutiny. Treat it as a guide to what lenders look harder at, not a list of acceptances.
| Default | Under 1 year old | 1 to 3 years old | 3 to 6 years old |
|---|---|---|---|
| Small phone, broadband or utility default | Closer review. Some lenders may consider it, but recency and status still matter. | Options may widen if it was a one-off and payments since are clean. | Often less influential, though it still has to fit the lender’s policy. |
| Larger card, overdraft or loan default | Narrower choice. The cause, whether it was settled, the deposit and affordability are all scrutinised. | More evidence is usually needed. A settled account and clean payments since may help. | A wider choice may return, although the amount and status still count. |
| Mortgage or other secured loan default | Usually the most restrictive, because it relates directly to a secured debt. | Still assessed closely. The lender may want strong evidence the cause has ended. | Can still affect criteria when older. Years of clean payments matter. |
 View it full size
Reading across, the default gets older. Reading down, the debt was bigger or closer to your home. Neither direction settles it alone: several defaults, an unpaid balance or fresh missed payments can change the picture even when each default is old or small.
All of that is an illustration built on experience, not a promise. Lender criteria are fluid and anything written down dates quickly, so speak to me before you rely on it. Finding the best deal open to you on the day is my job, and I will do that search on your behalf.
Are mobile phone and utility defaults ignored?
People often tell me it was only a phone bill. I understand why it feels different from missing a loan payment, and some lenders do treat a small communications or utility default more flexibly. A recent, unpaid or repeated one can still raise questions, whatever the account.
Mention it anyway, even if it seems too small to matter. The lender's current criteria decide how much weight it carries, and a surprise at underwriting is harder to fix than a line in the application.
How much does the size of a default matter?
A £40 final phone bill and an £8,000 loan default tell an underwriter different stories. A larger balance suggests more financial pressure, especially if it is still unpaid or sits alongside other missed payments.
There is no universal line such as defaults under £500 being ignored. Lenders handle the amount differently: some set limits, some combine it with age and account type, and others rely on credit scoring, so the figure has to be checked against current criteria.
Does paying off a default help you get a mortgage?
Paying a default shows the balance has been cleared, and some lenders view a satisfied default more favourably. It does not guarantee an approval, and the entry stays on your file until six years after the default date.
I would not tell anyone to spend deposit money on clearing it without comparing both positions first. Clearing the balance may help with some lenders, while a smaller deposit can close other routes.
Do you have to wait two years after a default?
Two years is not a universal approval point. More time helps, because the default reads as history rather than current pressure, but the account type, amount, status and your conduct since still need checking against the lenders available.
Several of our reviewers had been told to wait before they found us, and ten came to us after another broker or lender had already turned them down. Victoria, below, was remortgaging rather than buying, and a deal ending changes the timing in a way that is covered in remortgaging with bad credit.
I was struggling to remortgage because of a little blip on my credit report, I spoke to other brokers who told me I had bad credit and I’d have to wait! I was recommended to Angela who was really kind, she was straight talking but didn’t judge me… My mortgage has now offered and I am so relieved.
How is a default different from late payments or a CCJ?
- A late or missed payment: a payment was not made on time while the account stayed open. Lenders read missed payments differently again.
- Arrears: an overdue amount is still owing on an active account.
- A default: the lender treats the agreement as broken down.
- A CCJ: a court has confirmed the money is owed. See mortgages with a CCJ.
Of the four, the FCA’s own definition of impaired credit counts only arrears of three months or more in the last two years and CCJs over £500 in the last three. Defaults are not on its list, yet lenders still weigh them, as our UK bad credit mortgage statistics set out. Many files carry a mix. Check your credit report with each agency you can, and go by the dates on the reports rather than memory.
All of them pull the score down as well, which some lenders read before they read anything else. That is a separate question, covered in a mortgage with a low credit score.
What if the default on your file is wrong?
Do not build an application around an entry you believe is wrong. Contact the lender that reported it, raise a dispute with each credit reference agency showing it, and keep copies of bills, settlement letters and correspondence. While the lender checks, the agency can add a notice of correction to your report.
Checking your own credit reports does not harm your credit rating, because it is a soft search. A full mortgage application usually leaves a hard search, so resolve obvious errors first.
How do I look at a mortgage application with defaults?
As a bad credit mortgage broker in Essex, I start by getting the dates and account details straight. Then I look at why the default happened, whether it has been paid, how the rest of the file has been managed and whether the mortgage is affordable.
Only then do I research lenders. I package the case so the lender sees the explanation with the evidence, and I stay in touch with the lender and your solicitor through to completion. I advise clients with defaults across Essex, from Southend-on-Sea to Brentwood, and further afield by phone.
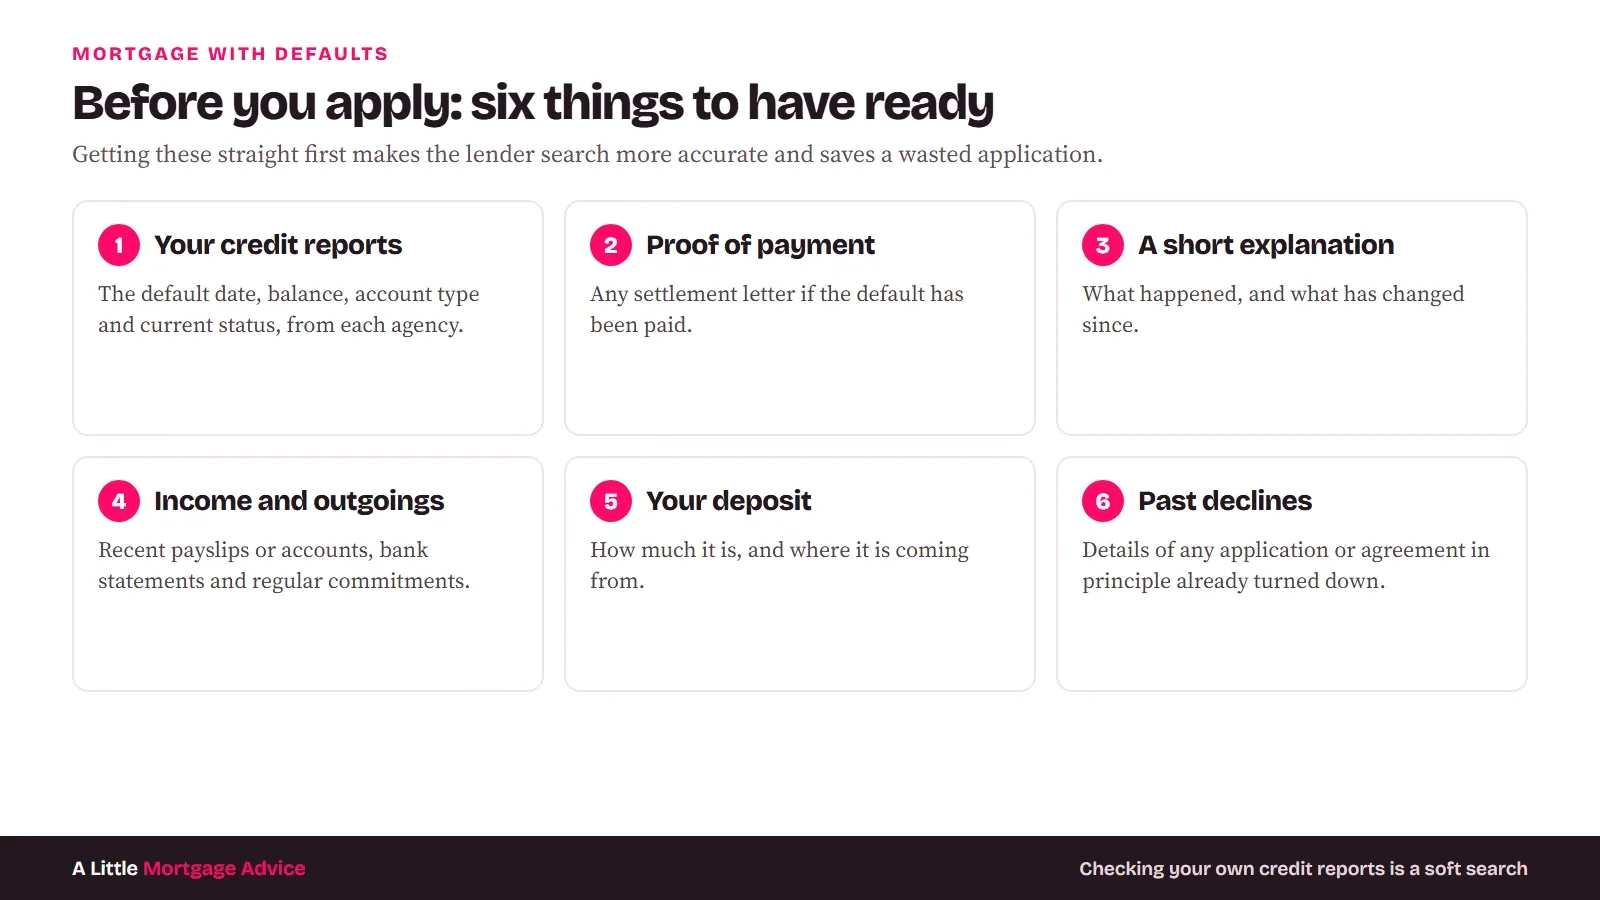
What to have ready when we speak:
- Credit reports showing the default date, balance, account type and current status
- Any settlement letter or proof of payment
- A short explanation of what happened and what has changed since
- Recent payslips or accounts, bank statements and details of regular commitments
- Your deposit, and where it is coming from
- Details of any application already declined
 View it full size
Every client also gets the financial M.O.T.: what the default is costing your file, what to fix first, and when a high street rate becomes realistic. A default is one of the marks we place most often as an adverse credit mortgage broker, alongside CCJs and missed payments.
Mortgages with defaults: your questions
Can you get a mortgage if a default is still unpaid?
It can be possible, although an unpaid balance may reduce the options. Whether clearing it first helps depends on the lender, the rest of the file and what it does to your deposit.
Do lenders ignore mobile phone defaults?
Not automatically. Some lenders are more flexible with a small, one-off communications default, but its age, status, amount and the rest of the credit file still matter.
How long does a default stay on your credit file?
Six years from the date of default. Paying it marks it as satisfied, but it only comes off early if it was recorded in error.
Can you get a mortgage with more than one default?
Possibly. The dates, balances, account types, reasons and recent payment history all carry more weight when several defaults appear.
Will a default mean a higher mortgage rate?
It can. The rate and the deposit needed depend on the product and the whole application, so compare the total cost of the options open to you.
Sources and further guidance
- Experian: how a default affects your credit profile, including how long it stays and how to dispute one
- ICO: credit files and defaults
Checked on 17 September 2026. Lender criteria change, so check the current position before relying on any of it.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Defaults on your credit file?
The age, size and type of default all matter. Find out where you stand before anyone runs a credit check.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.
Think carefully before securing other debts against your home. Your home or property may be repossessed if you do not keep up repayments on your mortgage or any other debts secured on it.