
How to Improve Your Chances of Getting a Mortgage with Bad Credit
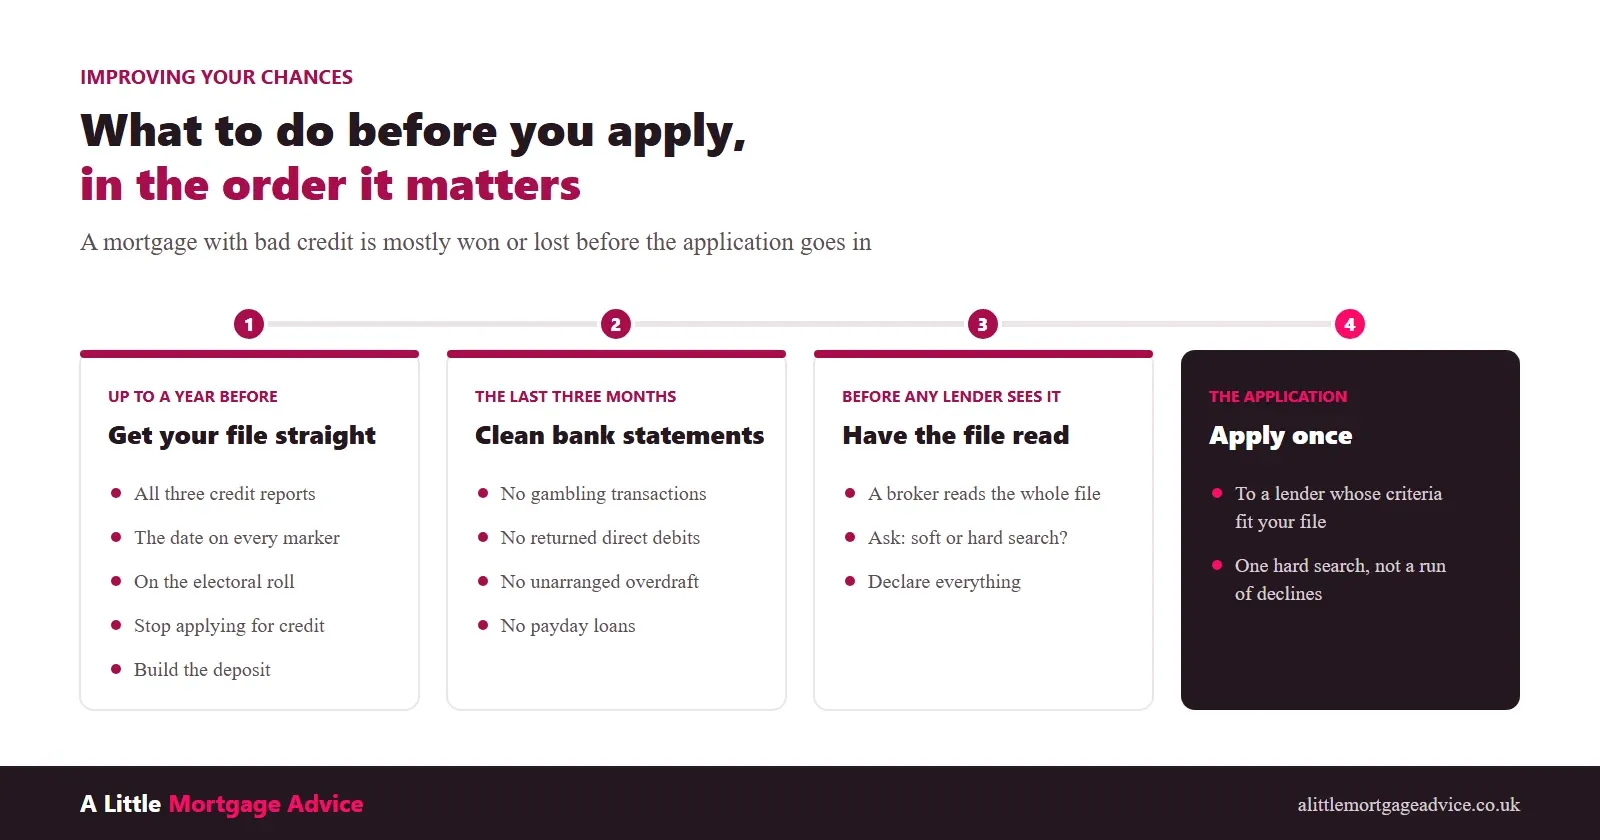
If you're looking to improve your chances of getting a mortgage with bad credit, you're in the right place. This is the work we do every day, and most of what makes the difference happens before you apply. Below is the order we give our own clients, from a year out to the day the application goes in.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Quick answer: What can I do to improve my chances of getting a mortgage with bad credit?
- Check all three credit reports and correct any errors.
- Register on the electoral roll.
- Pay every bill and credit card on time from now on.
- Stop applying for new credit.
- Keep your last three months of bank statements clean.
- Apply once, to a lender whose criteria fit your file.
What tends to be on the file
- Missed payments
- Late payments
- A default
- A CCJ
- A low credit score
- Declined elsewhere
Why speak to A Little Mortgage Advice about getting a mortgage if you have bad credit?
Because this is the work Angela Little is known for. She has been CeMAP qualified since 2014, has 30 years in financial services, and worked at specialist mortgage brokerages before founding A Little Mortgage Advice. Ten of our 181 Google reviewers say another broker or lender turned them down first.
The difference is made before a lender sees anything. Angela reads the file and does the pre-underwriting herself. As she put it to one client:
... all the information was there, the jigsaw pieces were just in the wrong places, so we took everything back to basics, put the puzzle in the right order, and the result is a mortgage with a highstreet lender ...
If the honest answer is "not yet", we will tell you, along with the steps to take. The first conversation is free. The phone is answered 9am to 9pm, seven days a week.
What improves your chances, and what only improves your credit score?
The number on a credit reference agency’s app is not the score a lender works from. There is no UK pass mark. Each lender scores the application on its own model, using your credit history, deposit, income and bank statements.
What that model asks is simple. What is on the file: missed payments, late payments, a default, a CCJ? How old is it, and how much was it for? Is it settled? Does the rest of the application make sense around it? Anything that changes those answers improves your chances. A few extra points on an app mostly changes how you feel.
Presentation counts as well. One client came to us after another broker offered him very high rates and fees, and in Angela’s words, "... we did our work upfront and packaged your case to the lender properly ..."
What should you do in the year before you apply?
Start early. Some of this takes months to show on your file.
- Get all three credit reports, from Experian, Equifax and TransUnion. Each can hold something the others do not. Your statutory reports are free. How to get and read them.
- Look hard for a CCJ you did not know about. 94 per cent of county court judgments in England and Wales were default judgments in April to June 2026, meaning the defendant did not respond to the claim (UK CCJ statistics), often because it went to an old address.
- Note the date on every marker. Most stay on your file for six years, and one that drops off in four months can change the whole plan: see how long after bad credit you can get a mortgage.
- Register on the electoral roll at your current address.
- Stop applying for credit, store cards and phone upgrades included. Every full application leaves a hard search other lenders can see.
- Build the deposit: a bigger one widens the lender list (what lenders really check).
... A year ago, she gave me a clear plan to improve my credit score and reduce my outgoings so I’d be in the best position to apply for a mortgage. I stuck to her advice, and now I’m officially buying my first home! ...
 See the original on GoogleTap to enlarge

 View it full size
Should you pay off a CCJ or default before you apply?
Mostly, yes. Timing decides how much it helps.
In England and Wales, pay a county court judgment in full within one calendar month of the judgment and you can have it removed from the register. After that month it stays for six years, and paying it gets it marked as satisfied instead. A satisfied CCJ, or a default marked as settled, reads very differently to an underwriter from one still outstanding.
Only 11.8 per cent of the 5.39 million records on the Register of Judgments were marked as satisfied at the end of March 2026 (UK CCJ statistics). If you have paid one, ask the court to record it.
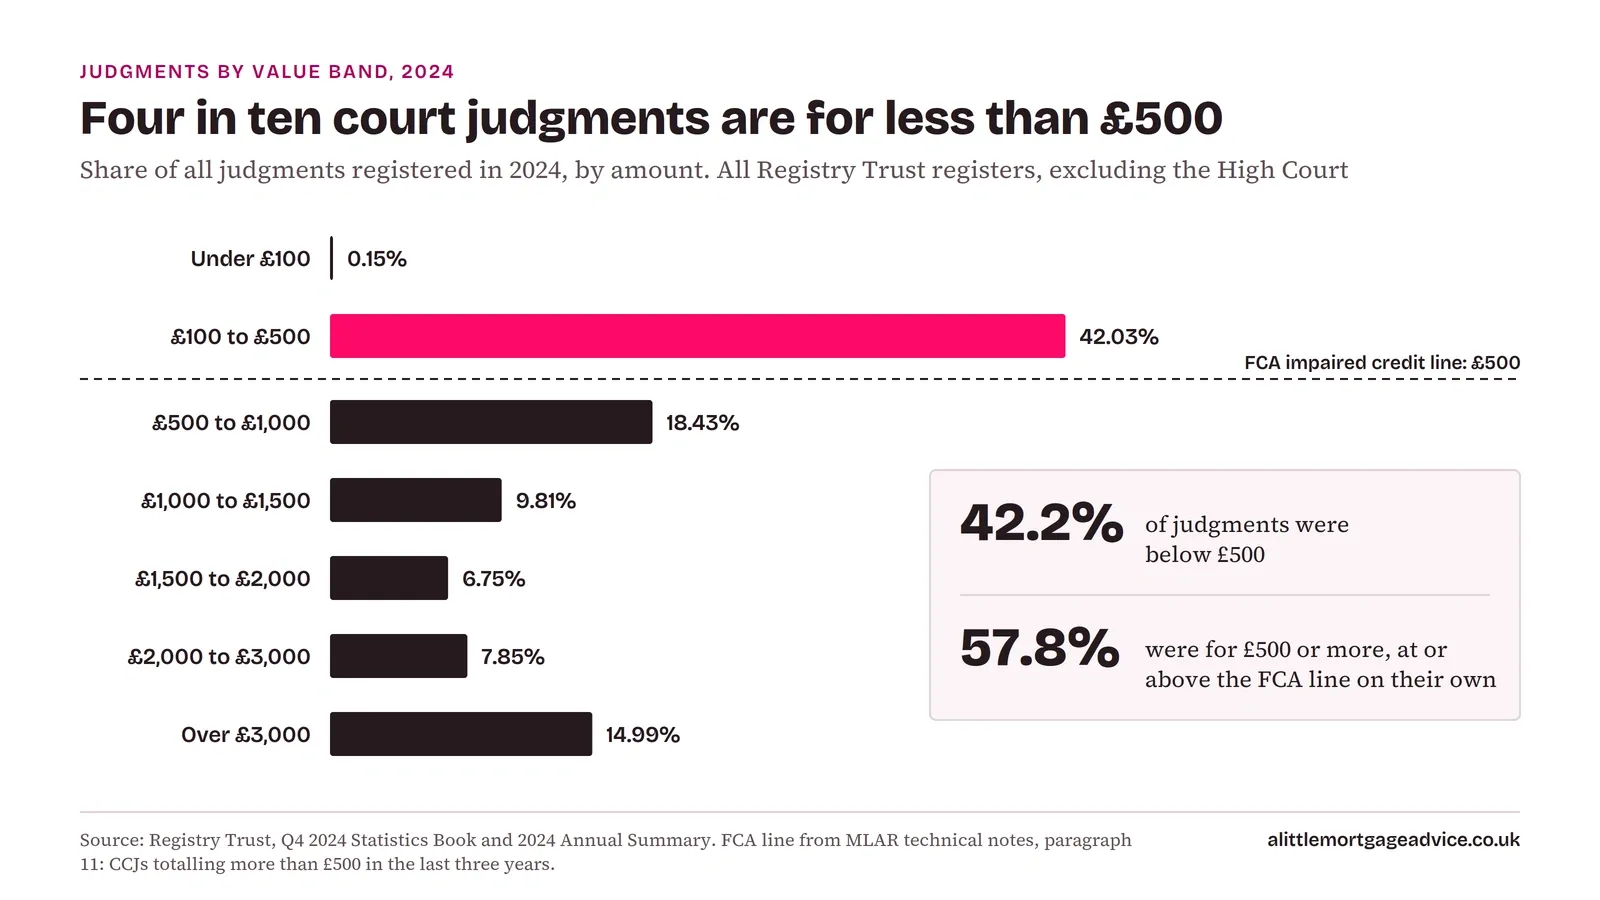
Size matters. The FCA counts a borrower as credit impaired where CCJs totalling more than £500 were registered in the last three years, though each lender still sets its own criteria.
 View it full size
An unsatisfied CCJ is not always the end of it:
... Got me a mortgage with ease even though I have a unsatisfied CCJ. ...
That mortgage was with a high street building society. More on a CCJ and defaults.
What are the red flags on a mortgage application, and which can you still fix?
Your bank statements, as much as your credit file. Most lenders ask for your last three months, and an underwriter reads them line by line, looking for:
- gambling transactions
- returned direct debits
- an unarranged overdraft, or living at the limit of an arranged one
- payday loans
- buy now pay later on top of everything else
Three clean months fix most of that. The lender reads the most recent ones. They cannot fix what sits on your credit history. A payday loan stays visible there, and some lenders will not consider anyone who took one in the last year.
Declare everything. An undisclosed debt reads far worse than a declared one, and if it is on your file, the lender will find it.
If your plan includes rolling unsecured debts into a mortgage, read consolidating debt into your mortgage first.
Why can applying to the wrong lender make your chances worse?
Because every full application leaves a hard search. A run of them tells the next lender a story before it has read a word of yours: someone rejected everywhere, when each lender was simply wrong for the file.
The decision in principle matters too. Some lenders run it as a soft search and others as a hard one, so ask which before anyone submits one in your name.
What our clients hear most often from elsewhere is "wait":
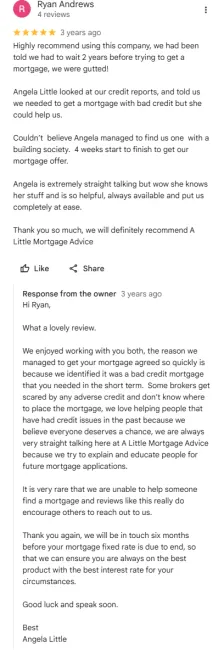
... we had been told we had to wait 2 years before trying to get a mortgage, we were gutted! ... Couldn’t believe Angela managed to find us one with a building society. 4 weeks start to finish to get our mortgage offer. ...
 See the original on GoogleTap to enlarge
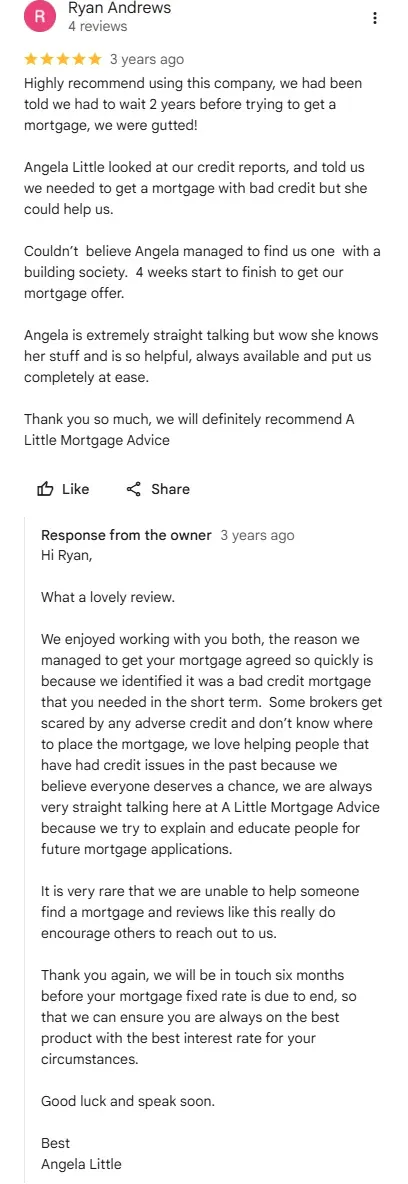
Angela’s reply to another client explains why it can go differently: "... we know our stuff and wouldn’t approach a lender if we thought the answer would be NO!"
If you'd like help with this, here's how to choose a broker with bad credit.
Should you wait, or apply now with a specialist lender?
It depends on your file. Anyone who answers without reading it is guessing.
Applying now usually means a specialist lender, a higher interest rate and a bigger deposit for the first deal, then a remortgage onto a high street rate once your markers are older. There is more of this lending than for years: UK lenders advanced £2.57 billion to credit-impaired borrowers in 2025, the highest annual total since 2008 (UK bad credit mortgage statistics).
... As me and my partner both had adverse credit, we thought we would need to wait before we could buy - but with Angela’s help, we were able to avoid a whole load of money going on rent. ...
Waiting costs rent and time. It pays when a marker is about to drop off, as Aura’s year showed.
The sum is the extra interest on a specialist rate against the rent you pay while you wait, and it has to include the fees, because a specialist lender’s arrangement fee is often higher and so is ours, since an adverse credit case takes more work than a standard one. We run it on your real numbers. See also bad credit mortgages.
Where these figures come from
- Court judgments: Registry Trust and the Ministry of Justice, via our UK CCJ statistics.
- Impaired credit lending and the £500 line: FCA MLAR, via our bad credit statistics.
- CCJs paid within a month: GOV.UK, CCJs and your credit rating.
- Reviews: our Google profile, verbatim, September 2026. They are individual experiences: every case is different and approval is never guaranteed.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Fair questions, straight answers
How likely am I to get a mortgage with poor credit?
It depends on the marker's type, age and size, whether it is settled, your deposit and your income. And on where it goes: a decline from your own bank says little about the rest of the market.
What is the easiest mortgage to get with bad credit?
No bad credit mortgage is easy, but some are more accessible. The usual route is a specialist lender with a larger deposit, at a higher interest rate, remortgaged later. Which lender depends on your file.
What would disqualify you from a mortgage?
Very little rules you out everywhere. What stops an application is specific to one lender: a marker too recent for it, affordability that does not work, a property it will not lend on, or something left off the application.
Can a guarantor help if I have bad credit?
Sometimes. Some lenders let a family member's income or savings support the application. It does not change your own file. The guarantor takes on real responsibility, so they should take independent legal advice first.
Ready for a straight answer?
Tell Angela where you're at - good credit, bad credit, or somewhere in between. You'll get honesty either way.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.