
Can I Get a Mortgage Working Part Time?
If you're looking to get a mortgage working part time, you're in the right place. The hours you work matter a lot less to a lender than people expect, so below is how your part-time pay becomes a borrowing figure, and what to do if your hours have only just changed or are about to.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Quick answer: How much can you borrow on a part-time income?
Lenders look at your yearly income rather than the hours you work. Many lend about four to four and a half times it, after your outgoings. On £18,000 a year that's roughly £72,000 to £81,000 on your own, and more with a partner's income alongside yours.
Why speak to A Little Mortgage Advice about a part-time mortgage?
Because the work on a part-time case is choosing the lender before anyone applies, as it is on all our specialist mortgages. Angela Little, CeMAP qualified since 2014, does that groundwork herself.
To be straight with you, none of our 185 Google reviews mentions part-time work. The one below is about how we go about a case:
... Angela was reassuring, she asked us lots of questions before going to the lender. When she was happy she approached a high street lender and got us an amazing rate. ...
Reviews are individual experiences. Every case is different and approval is never guaranteed.
A Little Mortgage Advice is a trading style of A Little Advice Limited, an appointed representative of The Right Mortgage Limited, which is authorised and regulated by the Financial Conduct Authority. Our FCA firm reference is 1006474.
Do lenders treat part-time income differently from full-time?
Mostly, no. A lender turns your regular pay into a yearly figure and checks it against your paperwork, as it would for anyone on a salary. FCA rules say that evidence has to come from a source independent of you, such as payslips, bank statements or tax documents.
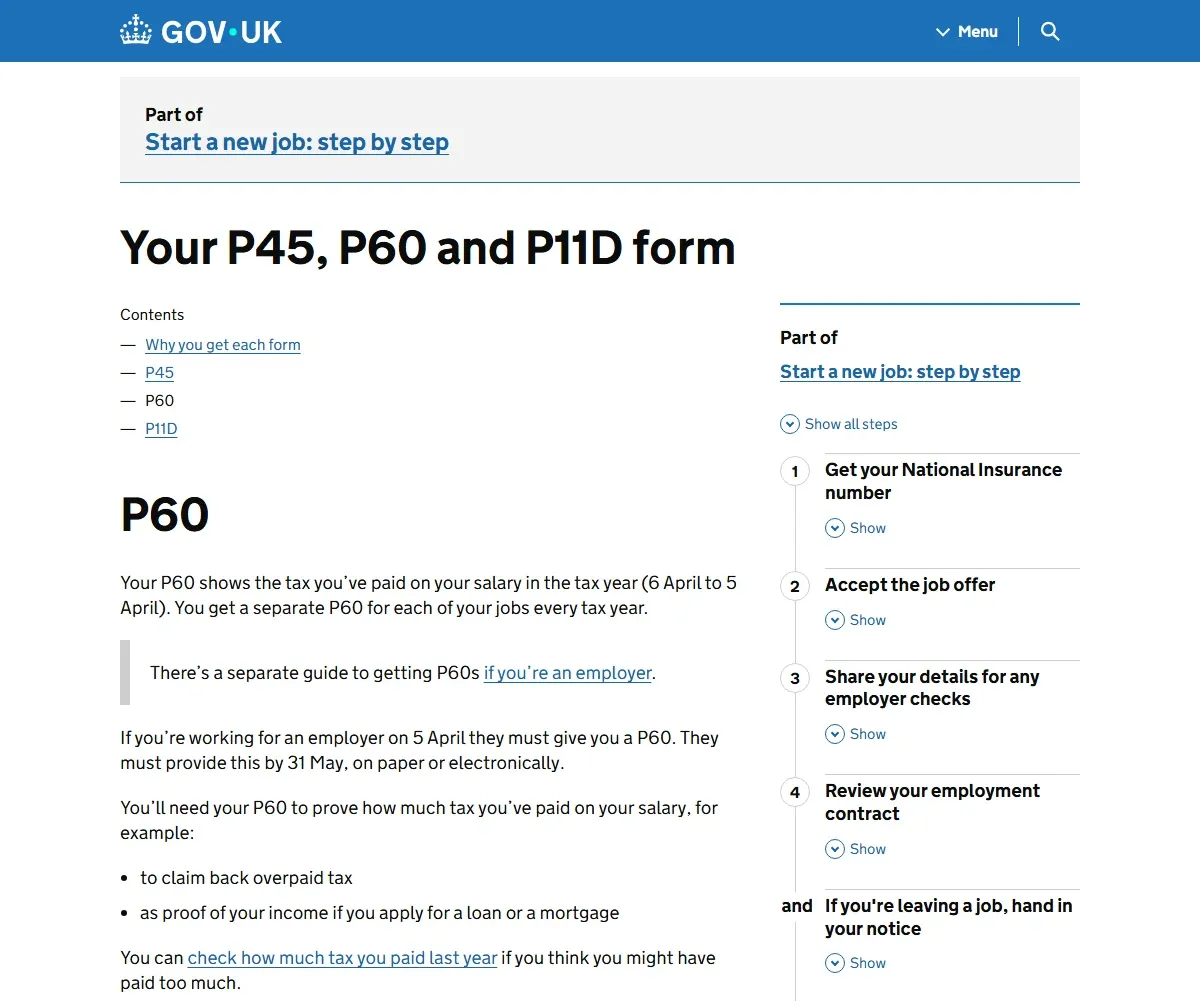
Your P60 is the one people forget. GOV.UK lists proving your income for a mortgage as one of its uses, and you get a separate P60 for each job you hold at the end of the tax year.
What changes from one set-up to the next is how easy the income is to prove:
| Your set-up | How lenders read it | What to have ready |
|---|---|---|
| Permanent part-time, fixed hours | Like any salary: monthly pay times 12, or weekly pay times 52 | Payslips and your latest P60 |
| Two part-time jobs | A lot of lenders count both, once the second has some history | Payslips and a P60 for each |
| Part-time job plus self-employment | Payslips for the job, tax figures for the business. See self-employed mortgages | Payslips, tax calculations and tax year overviews |
| Reduced hours after maternity leave | Your new contracted salary | New contract or a letter from your employer |
| Fixed-term contract | Time left to run, and past renewals | The contract and any renewals |
| Zero hours | Averaged over a period, where it's accepted | Up to twelve months of payslips |
How much can you borrow on a part-time salary?
Your annual income multiplied by the lender's income multiple, once your outgoings have been weighed up. Many lenders work at about four to four and a half times. At three part-time salaries, buying alone:
| Your annual salary | At 4 times | At 4.5 times |
|---|---|---|
| £15,000 | £60,000 | £67,500 |
| £20,000 | £80,000 | £90,000 |
| £25,000 | £100,000 | £112,500 |
These are illustrations, not offers. Each lender runs its own affordability check, and the real figure can come out lower if your monthly commitments are high.
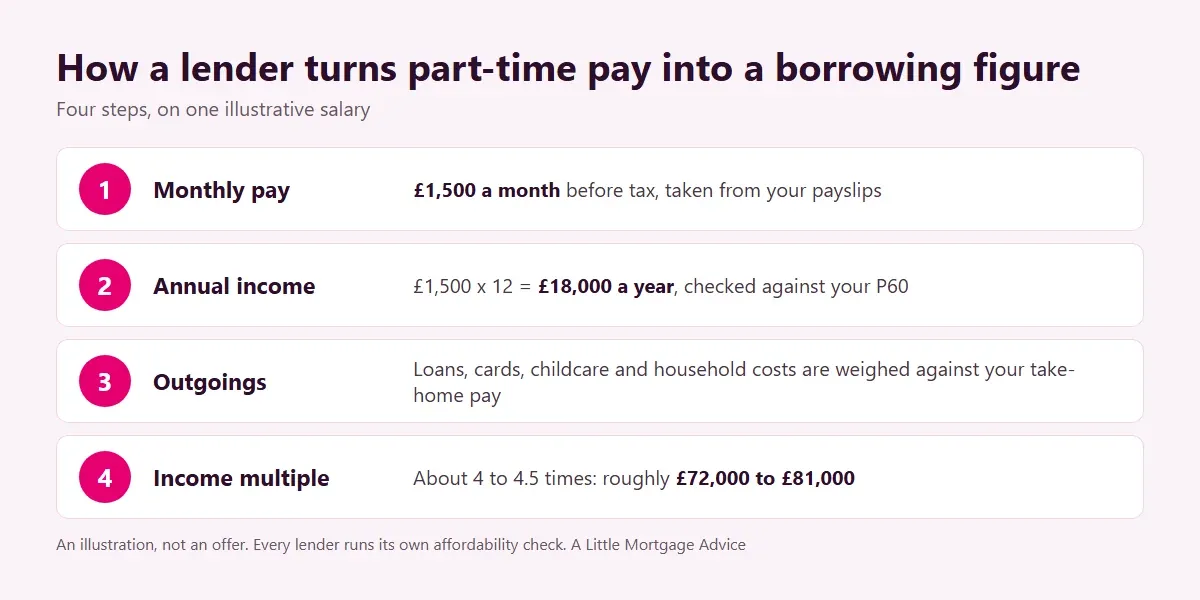
The four steps a lender goes through, on one illustrative salary:
- Monthly pay: £1,500 a month before tax, taken from your payslips.
- Annual income: £1,500 multiplied by 12 is £18,000 a year, checked against your P60.
- Outgoings: loans, cards, childcare and household costs are weighed against your take-home pay.
- Income multiple: about four to four and a half times, so roughly £72,000 to £81,000.
 View it full size
Full-time salary examples, and what they buy in Essex, are on our page about how much a first-time buyer can borrow.
Want to know what your own payslips would support? The first conversation is free. Call 01268 387898
Is there a minimum income or a minimum number of hours?
There's no minimum number of hours that we know of. The test is the yearly income and whether it covers the mortgage.
Some lenders do set a minimum income. The figure varies between lenders, and it's one of the first things we check on a part-time case, because it can rule a lender out before the multiple even comes into it.
Can a second job or other income count?
Yes, with a lot of lenders. FCA guidance says income can come from more than one job, and lenders that count a second job tend to want some history in it, often around twelve months. Child benefit and similar payments are lender by lender, and Universal Credit varies in the same way.
You've cut your hours after maternity leave. Which salary will a lender use?
The new one. If you've gone back on reduced hours, a lender works from your new contracted salary. If the cut is agreed but hasn't started yet, it still counts: FCA rules say a lender that knows, or should reasonably know, that your income is going to change has to allow for it.
Don't time an application to get in first. The lender has to be told, and a mortgage taken out on pay you no longer earn is one you could struggle to keep up.
One couple we helped buy their first family home came to us after problems with other brokers, with one of them self-employed and the other on maternity leave:
... With maternity leave and self employment it threw some curve balls in the way but Angela was a strong support throughout using her knowledge and expertise to come up with a solution. ...
That case was about maternity leave itself, not reduced hours afterwards.
Can you get a joint mortgage when one of you works part time?
Yes. A joint application puts both incomes into the sum, and both credit files get read. Buying as a couple is the most common way into a first home: in England in 2024-25, 40% of first-time buyer households were couples without dependent children and 25% were couples with children (English Housing Survey 2024-25).
| On your own | Joint | |
|---|---|---|
| Income the lender uses | £20,000 | £20,000 plus £35,000, so £55,000 |
| At 4.5 times, illustrative | £90,000 | £247,500 |
| Credit files read | Yours | Both |
You're both responsible for the whole mortgage, whoever earns more, and a problem on either credit file affects the application.
Do childcare costs and outgoings matter more on part-time pay?
They count the same, but they bite harder. FCA rules make a lender take full account of your income after tax, your committed spending and your household's essential costs before it decides you can afford the payments. On a smaller income, the same nursery bill takes a bigger share of what's left.
Card balances and car finance come into it too. Clearing a card before you apply can move the figure more than a few extra hours a week would.
Buying on your own on a part-time wage?
You'd be far from alone. In England in 2024-25, 29% of first-time buyer households were people buying on their own, according to our UK first-time buyer statistics.
On one part-time income the multiple runs out quickly, though. A bigger deposit or family help is how that gap gets closed. Our page on buying on a single income covers the lenders' side, and a guarantor or family-backed mortgage is another route if a parent can support the application.
Will working part time mean a higher rate or a bigger deposit?
Not of itself. Rates follow your loan to value and your credit file, so a part-time buyer with a 10% deposit and a clean file can look at the same range of deals as anyone else with that deposit and file. What differs is how much a lender will lend, and if the multiple leaves you short of the price, the difference has to come from your deposit. Our page on 5% and 10% deposit mortgages covers what a smaller deposit changes.
Final thoughts from us
What I'd want you to know if you work part time and you're thinking of buying:
- A lender looks at what you earn in a year. The hours behind it matter far less.
- Have your payslips and P60 ready, and check they tell the same story.
- If your hours are about to drop, tell us up front.
- Childcare, car finance and card balances come off before the multiple does its work, and on a smaller salary they can move the figure a long way.
- When one part-time salary won't stretch, a partner's income, a bigger deposit or family help is how the gap gets closed.
- Every figure here is an illustration, and approval is never guaranteed.
Part-time mortgages: your questions
Can I get a mortgage working 16 hours a week?
Yes, if the yearly income supports it. Sixteen hours a week at the National Living Wage for over-21s, £12.71 an hour, is about £10,575 a year. Four and a half times that is roughly £47,600. That won't go far in Essex, so a partner's income, a big deposit or family help normally fills the gap.
Does overtime on a part-time contract count?
It can. FCA guidance gives payslips over a period of time as one way to evidence overtime, and lenders differ on how much of it they'll use. Regular overtime across several months counts for more than one busy month just before you apply, and a lender may average it or count only part.
Does term-time only work count as full-year income?
If your salary is spread across twelve months, as it is on a lot of school contracts, your payslips already show the full-year figure and a lender reads it like any other salary. If you're paid only for the weeks you work, we'd start from the yearly total on your P60 and go from there.
What documents will I need?
Recent payslips, your latest P60, bank statements showing your pay going in, photo ID and proof of address. If you have a second job, bring the same for that one. Self-employed income on top needs your tax calculations and tax year overviews as well.
What is the 6 month rule for mortgages?
It's a rule some lenders apply: six months in your current job before they'll lend. Other lenders ask for less, and some will use a signed contract. Our page on getting a mortgage in a new job sets out the options.
Can I get a part-time mortgage with bad credit?
Yes, though the two together shorten the list of lenders, because each one narrows it on its own. A specialist lender's underwriter reads the file by hand. That helps when both need explaining. Our bad credit mortgages page covers how lenders treat CCJs, defaults and missed payments.
Sources
- Income evidence, affordability, known changes to income and staying with your lender: FCA Handbook, MCOB 11.6 (11.6.3R, 11.6.5R, 11.6.8R, 11.6.9G, 11.6.14R).
- Your P60: GOV.UK. Contains public sector information licensed under the Open Government Licence v3.0.
- National Living Wage from April 2026: GOV.UK.
- How much you can afford to borrow: MoneyHelper mortgage affordability calculator.
- First-time buyer households by type: our UK first-time buyer statistics page, from the English Housing Survey 2024-25.
- Reviews: our Google profile, verbatim, scraped 31 October 2026. They are individual experiences: every case is different and approval is never guaranteed.
Working part time and thinking of buying?
Send us your payslips and we'll tell you what they support. Lines are open 9am to 9pm, seven days a week, and the first conversation is free.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Ready for a straight answer?
Tell Angela where you're at - good credit, bad credit, or somewhere in between. You'll get honesty either way.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.