
Right to Buy With Bad Credit
Bad credit does not stop you qualifying for Right to Buy. Your landlord decides that on your tenancy and never sees your credit file.
Credit matters for the mortgage on the discounted price. That is the part I do, including for people other brokers have turned away.
 Whole-of-market access
 One adviser, start to finish
 Five-star client reviews
 No credit check to talk
Can I use Right to Buy if I have bad credit?
In most cases, yes. Right to Buy is a tenancy test, not a credit test, and your landlord never sees your credit file. The exceptions are a formal insolvency procedure that has not yet ended, and a possession order. Credit matters for the separate job of getting a mortgage on the discounted price, and that is the part I do.
Where you might be
- A default or CCJ on your file
- Missed payments in the last two years
- No savings for a deposit
- Your offer notice has arrived
- Behind on your rent
Does bad credit stop you qualifying for Right to Buy?
This is the misunderstanding I spend most time undoing as a bad credit mortgage broker in Essex. People assume a default or a CCJ rules them out of the scheme, so the form never gets sent. Qualifying and getting a mortgage are separate assessments, made by different organisations on different criteria.
Your landlord decides whether you can buy. They check that the home is your only or main home, that it is self-contained, that you are a secure tenant and that you have had a public sector landlord for at least three years. Those years do not have to be in a row or with the same landlord. Nobody looks at your credit file at that stage.
What does stop you buying under Right to Buy?
The money-related bars are narrow. Section 121 of the Housing Act 1985 names two situations that stop the purchase: a formal insolvency procedure that has not yet ended, or is still waiting to be decided, and a possession order against you for the home.
Defaults, CCJs and missed payments are not on that list.
Rent arrears sit in both conversations, though. Serious arrears are the usual route to a possession order, and they matter to a lender because your rent record is the nearest thing it has to a mortgage payment history. If you are behind now, talk to your landlord before you apply.
How much is a Right to Buy discount worth now?
Most of what you will read online about this is out of date. The percentages still look generous, but since late 2024 a cash cap decides what most people get.
| Years as a public sector tenant | Discount on a house | Discount on a flat |
|---|---|---|
| 3 to 5 years | 35% | 50% |
| 10 years | 40% | 60% |
| 15 years | 45% | 70%, the maximum |
| 20 years | 50% | 70% |
| 40 years or more | 70%, the maximum | 70% |
Since 21 November 2024 the maximum cash discount has been capped by area, between £16,000 and £38,000. Essex is in the East of England, where the cap is £34,000. You get whichever is lowest: your percentage, 70% of the value or the cap, and for almost every home in Essex the cap is the figure that counts. Before that change the cap was £102,400 outside London, so an article written before late 2024 describes a discount nobody can apply for now.
Your discount can also be cut if your landlord has built, bought, repaired or maintained the home in the last 30 years and those costs are high compared with its value. That rule is called the cost floor, and your landlord applies it when they work out your offer.
Can the Right to Buy discount replace a cash deposit?
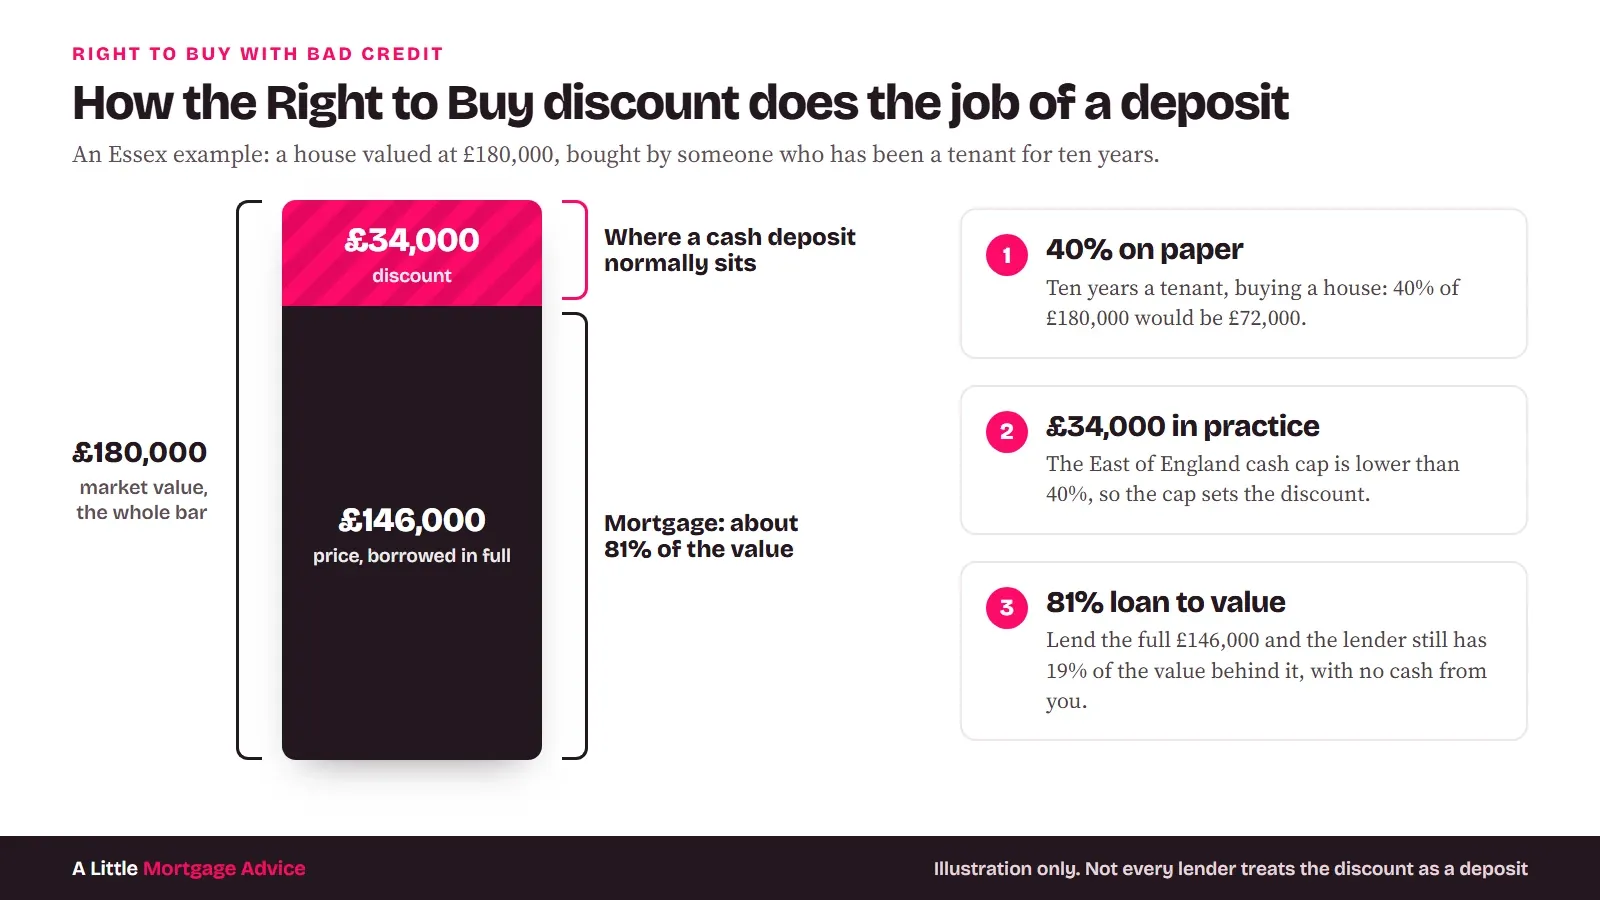
Often, and it is the reason Right to Buy can work when an ordinary purchase would not. The discount puts the price below market value, many lenders count that gap as your equity, and they lend against the discounted price. With real numbers, using the Essex cap:
- Your home is valued at £180,000.
- You have been a tenant for ten years and you are buying a house, so your percentage is 40%.
- 40% of £180,000 is £72,000, but the £34,000 cap applies.
- Your price is £146,000.
- A lender willing to lend the full price advances £146,000 and you put in nothing. Against the £180,000 value that is about 81% loan to value, so the lender still has 19% of the value behind the loan without any cash from you.
 View it full size
Take what follows as an illustration built on experience rather than a promise. Lender criteria are fluid and date quickly, so speak to me before you rely on it. Finding the best deal open to you on the day is my job, and I will do that search on your behalf.
Two caveats. Not every lender does this, and adverse credit narrows the group that will. The government's own guide for tenants says the same: some lenders treat the discount as your deposit and others do not. If a lender wanted 10% of the price in cash, you would need £14,600 of your own, and that is the first thing I check. If you have a small deposit to put in as well, low deposit mortgages covers what changes.
How does the Right to Buy process work, and where does the mortgage fit?
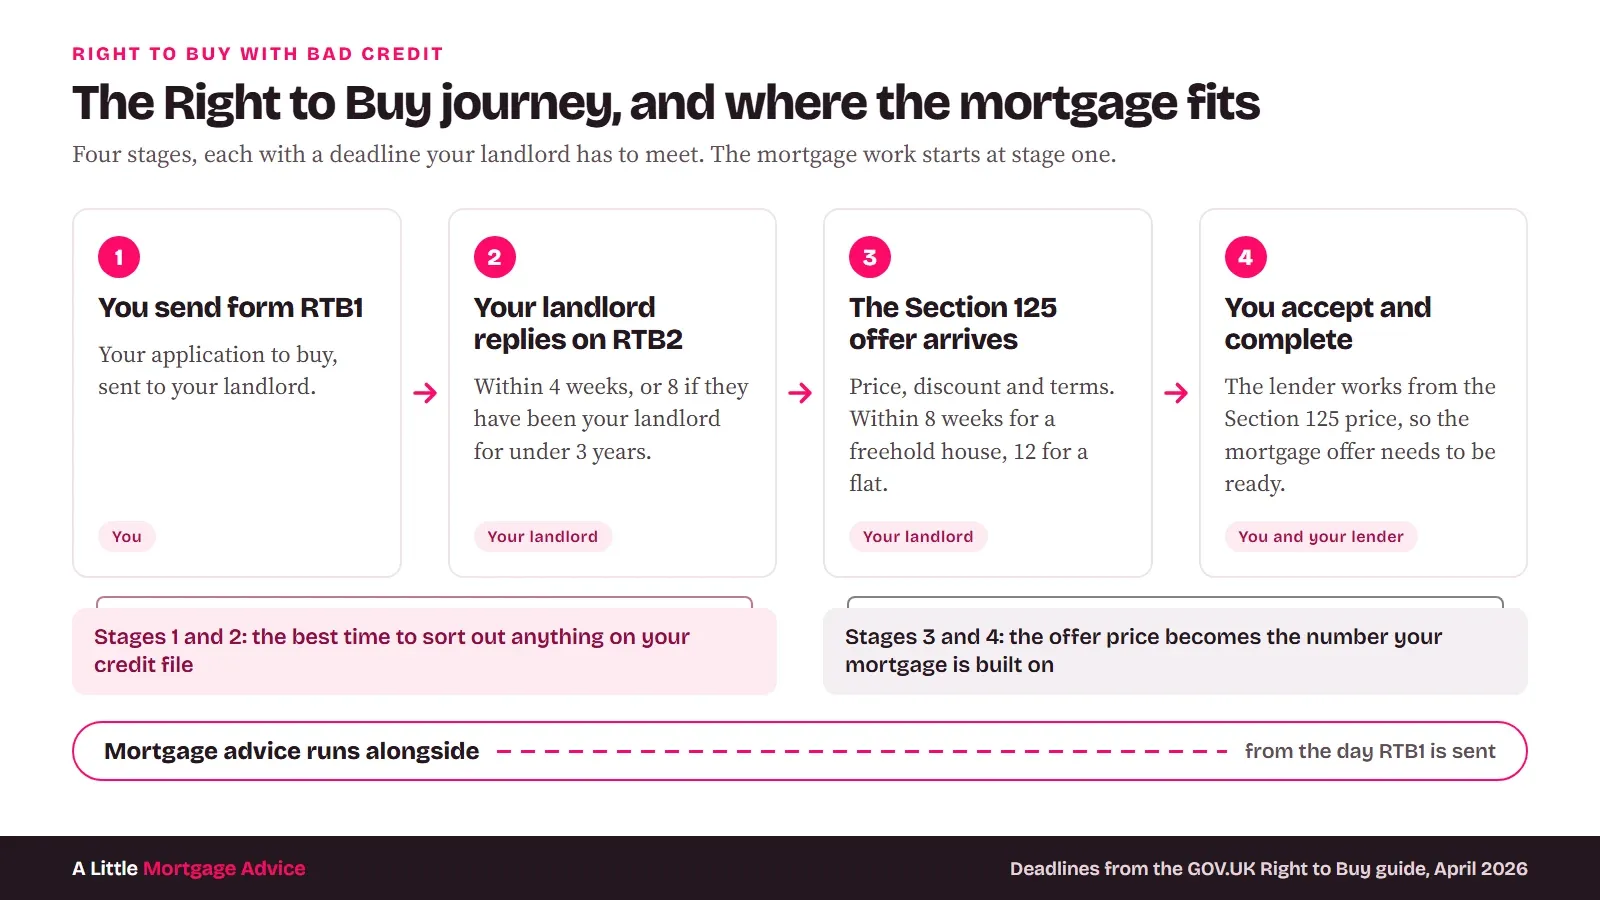
Knowing the running order stops people applying for a mortgage too early, or leaving it until the offer has already arrived.
 View it full size
- You send your landlord form RTB1. That is your application.
- Your landlord replies on form RTB2 within four weeks, or eight if they have been your landlord for less than three years. This confirms whether you have the Right to Buy.
- Your landlord sends a Section 125 notice: the offer, with the price, the discount and the terms. It should arrive within eight weeks for a freehold house, or twelve for a flat or leasehold house.
- The Section 125 price is the figure a lender works from, and the point at which I can tell you precisely what is achievable.
Your landlord cannot turn down your application because you have no mortgage agreed in principle, although some ask for one as part of their money laundering checks.
Please do not wait for the Section 125 notice before talking to me. The weeks while your landlord works through the paperwork are free time, and if something on your file needs fixing, that is when to fix it. Start by checking your credit report: it costs nothing and leaves no mark.
What kind of bad credit can still get a Right to Buy mortgage?
The type of problem, its age and whether it is settled matter far more than the fact that it exists. Age does most of the work: the same default at twelve months old and at four years old can put you with completely different lenders.
- CCJs. Satisfied and a year or two old opens up much of the market. Unsatisfied is harder but not closed: I placed a first-time buyer with an unsatisfied CCJ with a high-street building society. More on mortgages with a CCJ.
- Defaults. Judged on size, age and whether they are settled. A small, old, settled phone default is a very different conversation from a recent large one on a loan. See mortgages with defaults.
- Missed and late payments. One or two in the last couple of years is usually manageable. A cluster in one year pushes you towards specialist lenders. More in missed and late payments.
Some credit situations I do not place. If yours is one of them, I will tell you in the first conversation.
What does a difficult Right to Buy case look like?
A family came to me wanting to buy their home under Right to Buy, and on paper it looked very difficult. My client later called it a mammoth task, and it was.
The hard part was choosing which lender to accept. We went to two. The first came with a high rate, so we waited a short while until the case could go to a high-street lender, and that saved the family a lot of money. Morgan and I stayed with them through the final stages.
She took the time to listen and support our family with a RTB mortgage even though it looked like a mammoth task. She was there at every step to answer questions and to give guidance where needed... She was able to make our dreams come true. Securing the house for the future of my boys.
A second Right to Buy purchase, in late 2025, had a different problem: time. It needed a joint borrower sole proprietor mortgage, where someone joins the mortgage to help with affordability without going on the deeds, and that is difficult to place on a Right to Buy property. The council had set a two-month deadline, so we kept the solicitors moving as hard as the lender, and we got there.
What costs come with a Right to Buy purchase?
Right to Buy carries a cost an ordinary purchase does not. Sell within five years and you repay some of the discount: all of it in the first year, then 80%, 60%, 40% and 20%. The repayment is a percentage of what the home sells for, not the cash discount you received, so in a rising market you can repay more than you saved.
Sell within ten years and you must offer the home back to your landlord first.
Otherwise, budget for the usual costs: a valuation, conveyancing and possibly an arrangement fee, which can often be added to the loan. With adverse credit, expect a higher rate while the lender prices for the risk. That was the rate we waited out on the family's purchase above. My mortgage calculator will show you what the discounted price looks like as a monthly payment.
A Right to Buy purchase is often a first home too, so first time buyer mortgages covers the rest of the buying process.
Is it Right to Buy or Right to Acquire?
These get muddled all the time, including on other websites covering this topic. Right to Buy is for secure council tenants, and for housing association tenants who were council tenants when their home was transferred, under the Preserved Right to Buy. Right to Acquire covers many other housing association tenants, with much smaller discounts set as fixed cash sums. Check which scheme your landlord is offering before you plan around a number.
If you rent from a private landlord, neither scheme applies. A private landlord who agrees to sell to you below market value is offering a concessionary purchase, and the discount can work as a deposit in much the same way.
Is Right to Buy changing?
Yes, and sharply. The government's Social Housing Bill would raise the qualifying period from three years to ten, and cut discounts to 5% of the value, rising by 1% a year to a maximum of 15%, still within the cash cap. The Bill started in the House of Lords and was due for its second reading in the House of Commons on 10 September 2026. None of it is law yet, so the three-year rule and today's discounts still apply.
If you already qualify and have been putting off the form, compare 35% with 5% before you decide to wait.
Right to Buy with bad credit: your questions
Does bad credit stop me qualifying for Right to Buy?
No. Your landlord decides eligibility on your tenancy, not your credit file. The only money-related bars are a formal insolvency procedure that has not yet ended and a possession order against you for the home.
Can I get a Right to Buy mortgage with no deposit?
Often, because many lenders treat the discount as your equity and lend against the discounted price. Adverse credit reduces how many will, and some want cash on top, so check your position before counting on it.
How much is my Right to Buy discount in Essex?
Take your percentage from the table on this page, then compare it with the cash cap for your area. In Essex the cap is £34,000, and for most people the cap rather than the percentage sets the figure. Your Section 125 notice confirms it.
Will applying to several lenders hurt my chances?
It can. Each full application usually leaves a hard search, and several in a short period, especially with declines among them, reads badly to the next underwriter. That is why the lender choice comes first, and nothing touches your credit file without you being told.
Do I need a broker for a Right to Buy mortgage?
Not for the scheme itself. But many lenders who consider adverse credit alongside Right to Buy only deal through brokers, so going direct can quietly limit your options.
Sources and further guidance
- GOV.UK: Right to Buy, buying your council home, including the discounts and cash caps
- GOV.UK: Your Right to Buy your home, a guide for tenants, April 2026
- Housing Act 1985, section 121: when the right to buy cannot be used
- GOV.UK: Right to Buy overhaul to safeguard social housing, 28 April 2026
All checked on 16 September 2026. Scheme rules and lender criteria change, so check caps, qualifying periods and lending criteria with your landlord and with me before relying on them.
Based in Benfleet, Essex - advising clients across the whole of the UK.
Buying your home under Right to Buy?
Tell us what is on your credit file, how long you have been a tenant and whether your Section 125 notice has arrived. You will get a straight answer on what looks achievable.
Lines are open 9am to 9pm, seven days a week, and the first conversation is free.